Retirement planning is easy to push down the to-do list, especially when retirement still feels years away. But waiting can mean missed opportunities involving taxes, investments, health care, and retirement income. Here are five common reasons people put off creating a written retirement plan and why starting earlier can make a difference.
1. Conflicting Priorities Make Planning Feel Impossible
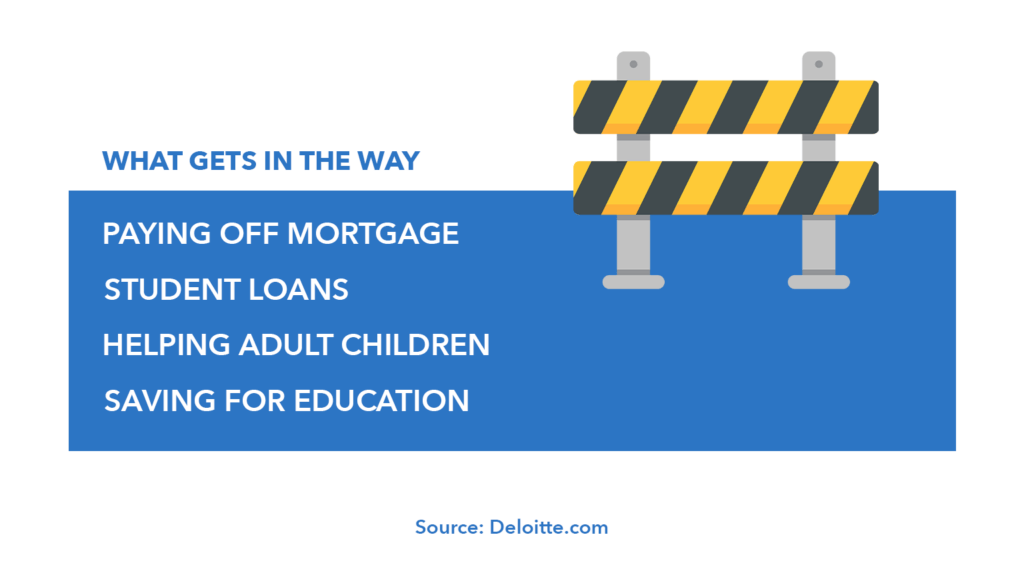
For many people in their 50s and early 60s, retirement planning is competing with some of the busiest years of life. Careers may be demanding. Adult children may need help with student loans or a down payment on a home. Grandchildren enter the picture. Aging parents may need additional support.
Retirement is still on the list, but it can easily move below the needs that feel more immediate.
The problem is that some retirement strategies are time-sensitive. Loren Merkle, CFP®, RICP®, Certified Financial Fiduciary®, explains, “Not having a plan and not having a written plan, that might prevent you from implementing some strategies that, at age 55 or somewhere in your 50s, in those pre-retirement years and in those early retirement years, that can cost people.”
Consider a hypothetical couple, Tom and Heidi. They are in their 60s and still working while supporting aging parents and helping their children. They plan to focus on retirement once life settles down. One year passes. Then two. Eventually, they retire without a plan.
Those years could have included opportunities to evaluate Roth conversions, build a long-term tax strategy, or adjust investments before retirement.
Chawn Honkomp, CFP®, RICP®, Certified Financial Fiduciary®, CPA, says, “We help people have a long-term tax plan so that we can help people identify each and every year what tax strategies they should be considering.”
Investments also take on a different role in retirement. While working, the focus is often on accumulating savings. In retirement, those savings may need to become a regular source of income. That change can affect how much investment risk makes sense.
2. Fear of what the numbers will actually show
Sometimes the reason for delaying retirement planning is much simpler: People are afraid they will discover they do not have enough.
Avoiding the numbers may postpone an uncomfortable answer, but it also shortens the amount of time available to address a potential gap.
“Sometimes people just think it’s easier not to know,” Loren says. “It’s easier not to know what retirement could look like from a financial standpoint because, you know, it’s easy not to face reality sometimes.”
A written retirement plan can provide a clearer picture of whether current savings, income, and spending expectations support the retirement someone has in mind. If the numbers do not line up, discovering that five or 10 years before retirement may provide more options than discovering it days before leaving work.
Those changes do not necessarily have to happen all at once. Someone may be able to save more, adjust a retirement date, reconsider spending, or implement other strategies over several years.
As Loren explains, “You do tackle this in an evolution because a lot of things do change. Your vision for your retirement could be different four years from now than what it is today.”
3. Overconfidence and Not Knowing What You Don’t Know
One of the challenges of retirement planning is preparing for a retirement date you may not get to choose.
Transamerica Institute surveyed 2,500 workers age 50 and older. Sixty-six percent expected to retire after 65 or did not plan to retire at all. Yet 58% of people retired before age 65, with a median retirement age of 62. Only 31% of those surveyed had a backup income plan if they were forced to retire sooner than expected.
That gap matters because health changes, layoffs, and other circumstances can move retirement forward unexpectedly.
“We can have your plan, but the employer might have their own plan,” Chawn says. “Your health can change.”
A written plan can model what retirement might look like at several different ages rather than relying on one target date. It can also uncover opportunities while there is still time to act.
One example is retirement savings. Once someone is over age 50, higher contribution limits may allow them to put additional money into a 401(k) or other employer-sponsored retirement plan. Several years of additional contributions can change the retirement picture.
There can also be misconceptions about what happens when retirement savings are held in more than one account.
Here is a simplified hypothetical example for illustrative purposes. Consider $100,000 invested in a 401(k). If the entire $100,000 earns a 10% return, the earnings would be $10,000.
Now divide the same $100,000 between two accounts: $50,000 in a 401(k) and $50,000 in an IRA. If both earn the same 10% return, each earns $5,000, for the same total of $10,000.
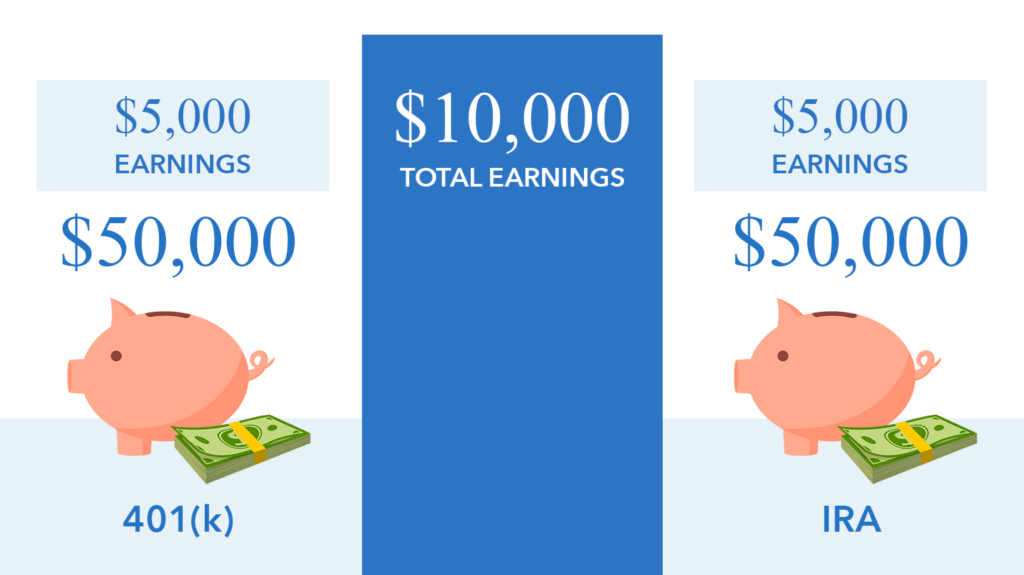
“So, your earnings are the same no matter how many buckets you have it in, assuming the same rate of return,” Loren says.
For some employer-sponsored plans, age 59½ may also create an opportunity to consider an in-service distribution to an IRA. Whether that option is available and appropriate depends on the specific plan and individual circumstances.
4. Distrust of Financial Institutions
Retirement planning can involve investments, taxes, Social Security, health care, income, and estate considerations. When people do not fully understand how financial products or advisory relationships work, distrust can follow.
Fees are one area where questions are especially important.
Loren says one of the questions people should ask both current and prospective financial professionals is what they are paying in fees. An advisory fee may be only one layer of the overall cost. Investments themselves can have additional expenses.
“You want to be informed,” Loren says. “You want to know what you’re paying.”
Before choosing someone to work with, consider bringing a written list of questions. Ask about credentials, the fiduciary standard, advisory fees, investment expenses, and how recommendations are made. Then continue asking follow-up questions until you understand the answers.
5. The Do-It-Yourself Mentality
Some people have successfully managed their finances for decades and see no reason to change when retirement approaches. Doing it yourself is an option, but retirement introduces decisions that may not have existed during the accumulation years.
The challenge is not necessarily understanding each individual piece. It is understanding how the pieces affect one another.
A Social Security decision can affect taxable income. Tax decisions can affect Medicare costs. Investment withdrawals can affect taxes. Health care expenses can change income needs. Spending decisions can affect how long retirement savings may last.
That is why a retirement plan needs to consider more than investments alone.
The RetireSecure Roadmap is the name of the comprehensive, customized retirement plan we build with the families and individuals we serve. It brings together six pillars of retirement planning: lifestyle, income, taxes, investments, health care, and legacy. Looking at those areas together can make it easier to see how one decision may affect another.
A Written Plan Turns Questions Into Decisions
There may never be a year when work, family responsibilities, and finances all become simple enough that retirement planning naturally rises to the top of the list.
That makes time one of the most valuable parts of the planning process.
Starting earlier does not mean every retirement decision needs to be made today. It means creating a clearer picture of where you are, identifying potential gaps, and understanding which strategies may deserve attention while there is still time to consider them.
As Loren explains, “As you build your plan, it will account for your current vision and implement the strategies, allow you to implement the strategies that are necessary for today’s vision, but also tomorrow’s.”
—
Watch the full episode on YouTube and learn more about common reasons people put off creating a written retirement plan and why starting earlier can make a difference.
Sources:
(September 2023). Life in Retirement: Pre-Retiree Expectation and Retiree Realities. Transamerica Institute. https://www.transamericainstitute.org/docs/library/research/life-in-retirement-preretirees-expectations-retiree-realities-report-september-2023.pdf?sfvrsn=58f037dc_11
(April 2022). Closing the Gap in US Retirement Savings. Deloitte Insights. https://www.deloitte.com/us/en/insights/industry/financial-services/closing-retirement-savings-gap.html