Many people spend decades accumulating retirement accounts, investments, and financial products, but far fewer have a written strategy showing how everything works together. This blog explores the difference between owning financial tools and having a retirement blueprint, how recent tax law changes may impact retirement decisions, and why planning for income, taxes, inflation, health care, and longevity can help create greater confidence in retirement.
A Retirement Plan Is More Than a Collection of Accounts
Most retirees arrive at retirement with a collection of financial tools they’ve accumulated over a lifetime—401(k)s, IRAs, bank accounts, life insurance policies, trusts, and investment accounts. The problem is that having tools doesn’t automatically create a strategy.
As Retirement Planner Loren Merkle explained, many people reach retirement only to discover that they have “tools everywhere. No organization.”
Throughout a working career, it makes sense to gather these financial tools as different needs arise. But retirement introduces a new challenge: determining how all those pieces work together to provide income, manage taxes, cover health care costs, and support long-term goals.
Without a written plan, retirees often find themselves making important decisions independently and hoping those decisions produce the desired outcome.
As Loren put it, “You end up hoping that those decisions work out. But then you realize hope is not a plan.”
Why a Written Retirement Plan Matters
A retirement plan is much more than a single sheet of paper. It should address multiple areas of retirement and show how they interact with one another.
Retirement Planner Haley Gutschenritter emphasized that retirement decisions rarely exist in isolation.
“What you do with your income is ultimately going to affect your tax plan, and your taxes are going to affect what you have to pay for health care.”
When retirees can see those relationships laid out in writing, it can help provide greater clarity around how retirement decisions may work together. Rather than wondering whether individual decisions are working together, they can understand how one choice affects another.
According to Haley, “It provides confidence. It’s a blueprint.”
Retirement Planning Is Different Than Investment Management
Many people spend years working with professionals who focus primarily on growing investments. That’s appropriate during the accumulation years when saving and investing are the primary objectives.
Retirement introduces a different set of questions:
- When should Social Security begin?
- How will retirement income be generated?
- What strategies can help reduce taxes?
- How will health care costs be covered?
- How can assets last through a decades-long retirement?
Haley noted that retirement often requires a broader planning approach.
“Once you get to 50 and 60, now you’re asking yourself, ‘Well, what am I going to do with Social Security? How am I going to get paid? How am I going to afford health insurance?'”
Those questions extend beyond investment performance and require a coordinated retirement strategy.
New Tax Rules Could Change Existing Plans
Just as construction projects sometimes require blueprint revisions, retirement plans need updates when laws change.
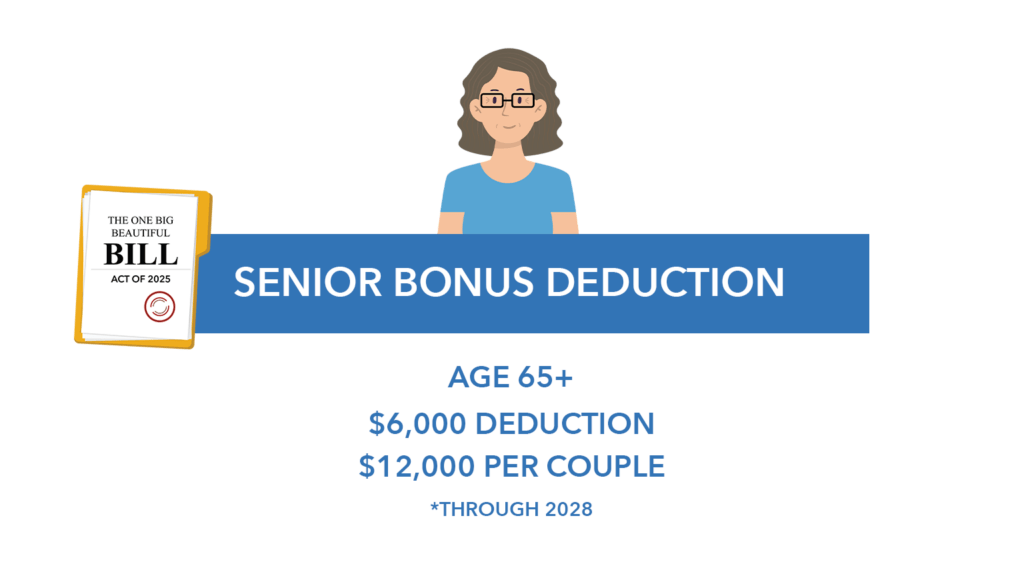
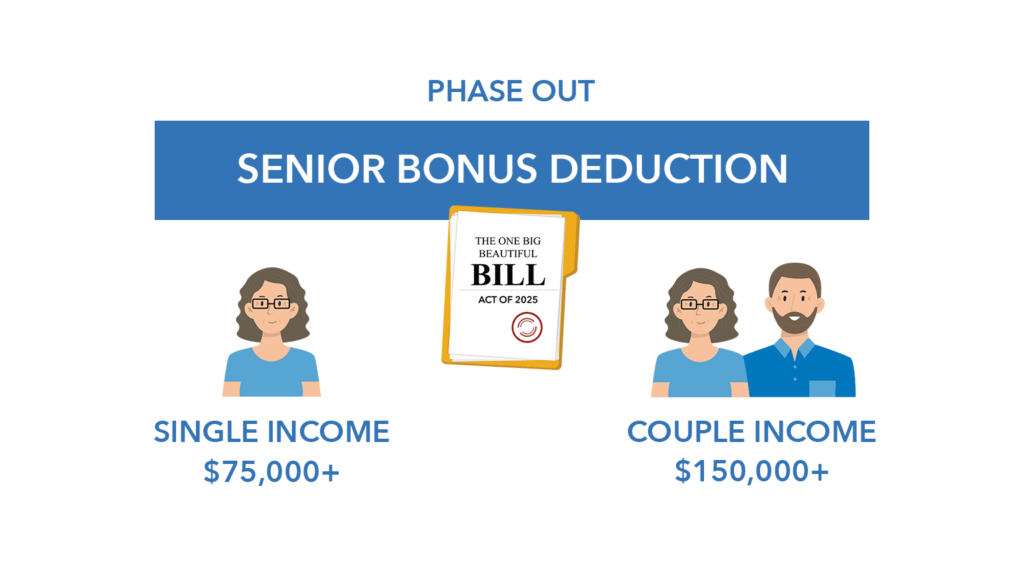
The One Big Beautiful Bill Act introduced an additional senior bonus deduction that may create opportunities for some retirees while complicating tax planning for others.
Loren explained that the legislation created a new senior bonus deduction available through 2028. Individuals age 65 and older may qualify for an additional $6,000 deduction, while married couples filing jointly may qualify for up to $12,000. The deduction begins to phase out once modified adjusted gross income exceeds $75,000 for single filers and $150,000 for married couples filing jointly.
That change can influence decisions involving Roth conversions and taxable income levels.
As Haley explained, “This creates a lot of nuance with the tax planning.”
The key takeaway is that tax strategies should not be viewed in isolation. A decision that appears beneficial on its own could affect other opportunities within the overall retirement plan.
The Risk of Having Too Much in the Market
Retirees who depend heavily on stock market investments for income may be forced to withdraw money during market downturns. Taking withdrawals while account values are declining can permanently impact long-term retirement outcomes.
Market volatility is a normal part of investing. The challenge is ensuring that short-term income needs don’t force difficult decisions during turbulent periods.
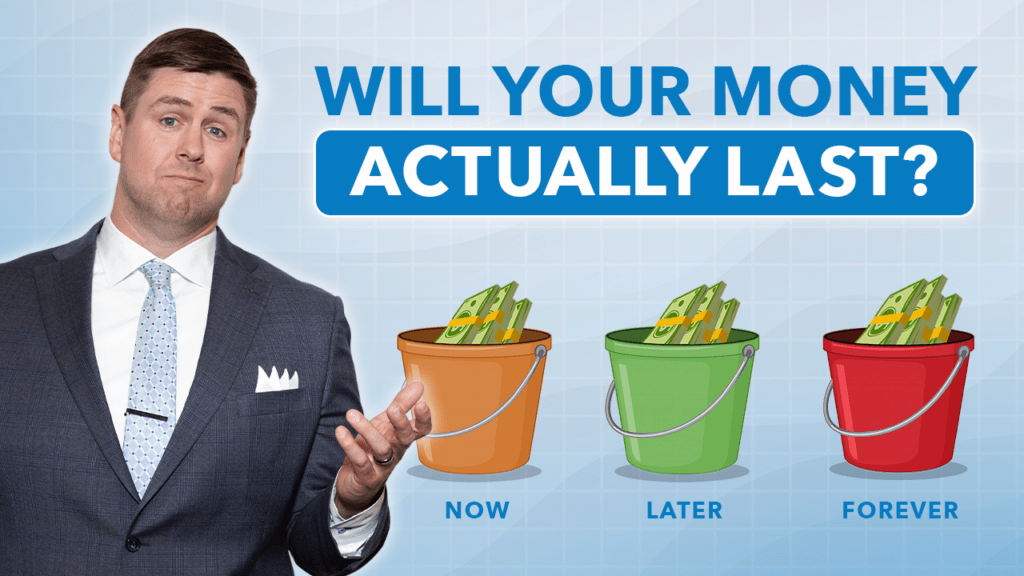
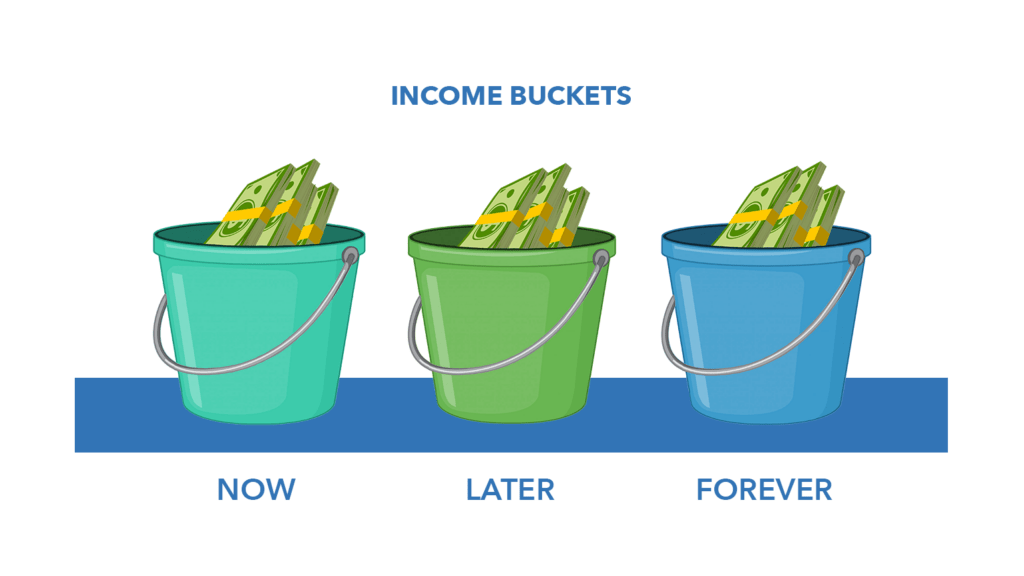
To address this, Haley often discusses a three-bucket strategy that separates retirement assets by purpose.
The approach includes:
The Now Bucket
Money needed immediately, including checking accounts, emergency savings, and short-term reserves.
The Later Bucket
Funds needed in the near future, typically invested more conservatively with a focus on income and stability.
The Forever Bucket
Long-term growth assets designed to help combat inflation and support future spending needs.
As Haley explained, “Your retirement savings has three different jobs. It’s not just one big pile of cash.”
Planning for a Retirement That Could Last 30 Years
One of the biggest retirement risks isn’t market volatility—it’s longevity.
According to the discussion, a person who reaches age 65 today may spend 20 to 30 years or more in retirement. That means decisions made today could affect income decades into the future.
Loren highlighted one of the most common concerns retirees face:
“One of the biggest concerns of most people going into retirement is running out of money before you run out of time.”
A written retirement plan can help project income needs, account for inflation, evaluate tax strategies, and stress-test retirement outcomes over long periods.
Inflation and Taxes Require Long-Term Planning
Inflation may seem manageable in a single year, but its impact compounds over time.
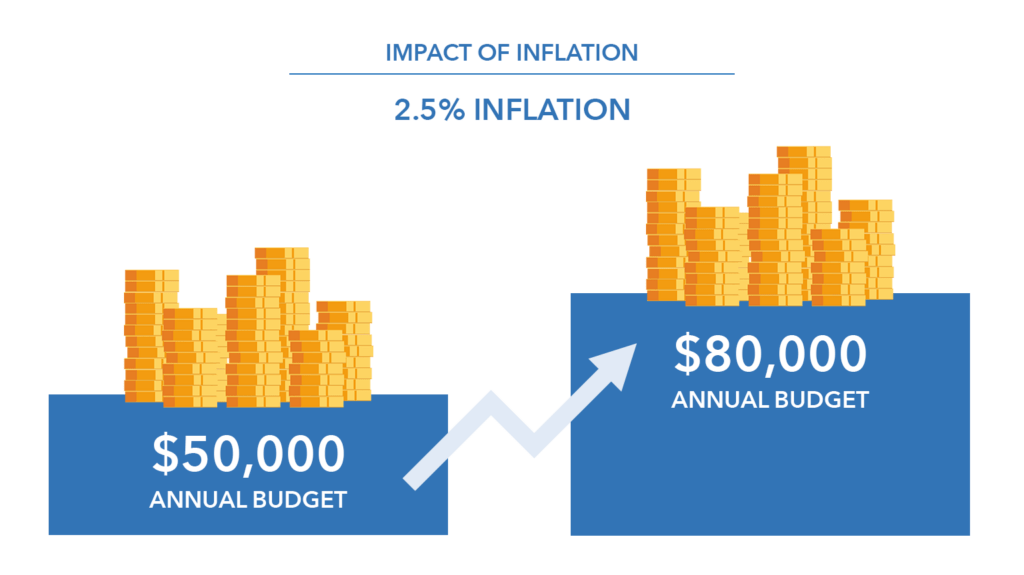
Loren illustrated this with a hypothetical example: a $50,000 annual budget today could require more than $80,000 annually in 20 years, assuming 2.5% inflation.
Taxes can have an equally significant impact.
Loren described retirement taxes as “the number one wealth eroding factor when it comes to your portfolio over the course of your retirement.”
Strategies such as Roth conversions, tax-loss harvesting, and Social Security optimization may help reduce lifetime taxes, but their effectiveness often depends on the broader retirement picture.
Haley also pointed out that tax planning becomes even more important after the loss of a spouse because tax brackets narrow significantly for single filers.
The Value of a Retirement Blueprint
A well-designed retirement plan coordinates lifestyle goals with income, taxes, investments, health care, and legacy planning.
Loren described the purpose of a retirement blueprint simply:
“It’s not hope. It’s a plan.”
For many retirees, that distinction can make all the difference. A collection of financial tools may help build wealth, but a written retirement plan helps turn those tools into a coordinated strategy designed to support retirement for decades to come.
Watch the full episode on YouTube and learn more about why planning for income, taxes, inflation, health care, and longevity can help create greater confidence in retirement.