As retirement gets closer, the financial guidance you need may change. Understanding the difference between investment-focused advice and comprehensive retirement planning can help you identify whether your current approach addresses income, taxes, Social Security, health care, investments, lifestyle, and legacy.
—
For decades, much of your financial life may have centered on one goal: saving and investing for the future.
But eventually, the questions change.
How will you turn those savings into income? When should you take Social Security? How much could you owe in taxes throughout retirement? How will you pay for health care? What happens financially if your spouse dies first?
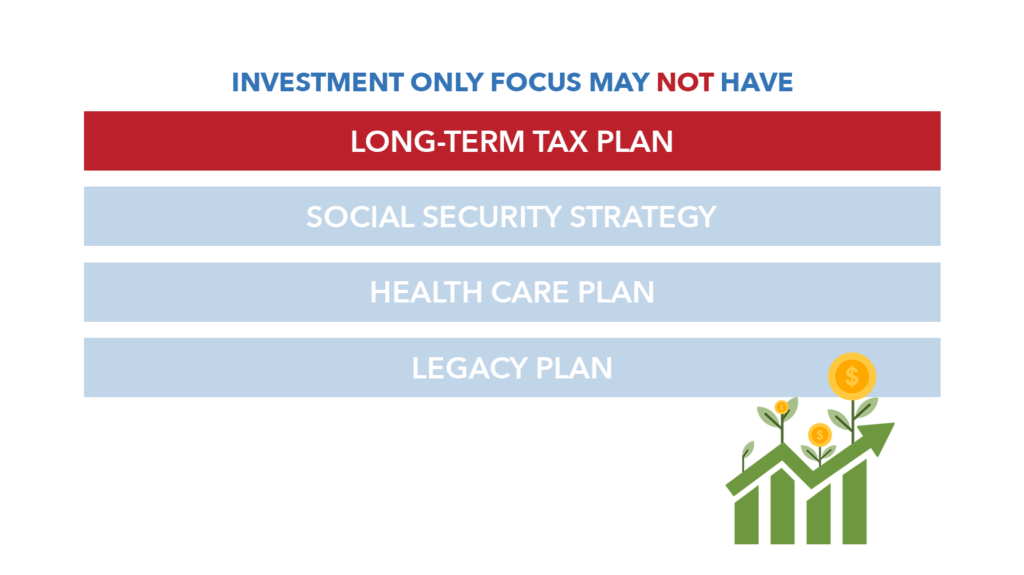
Those questions illustrate an important distinction between an investment-focused financial advisor and a retirement planner.
Different Guidance for Different Phases of Life
Investment-focused advisors and retirement planners can both play important roles. The difference is often the phase of life they are helping you navigate.
“The biggest misconception is that all people who work with money, all advisors, do the same thing,” says Loren Merkle, CFP®, RICP®, Certified Financial Fiduciary®.
During your working years, the emphasis is often on accumulation: contributing to a 401(k), investing those savings, and building a portfolio over time. Conversations may center on portfolio construction, investment returns, and performance compared with benchmarks.
As retirement approaches, the focus begins to shift from accumulating money to determining how those savings will support your life.
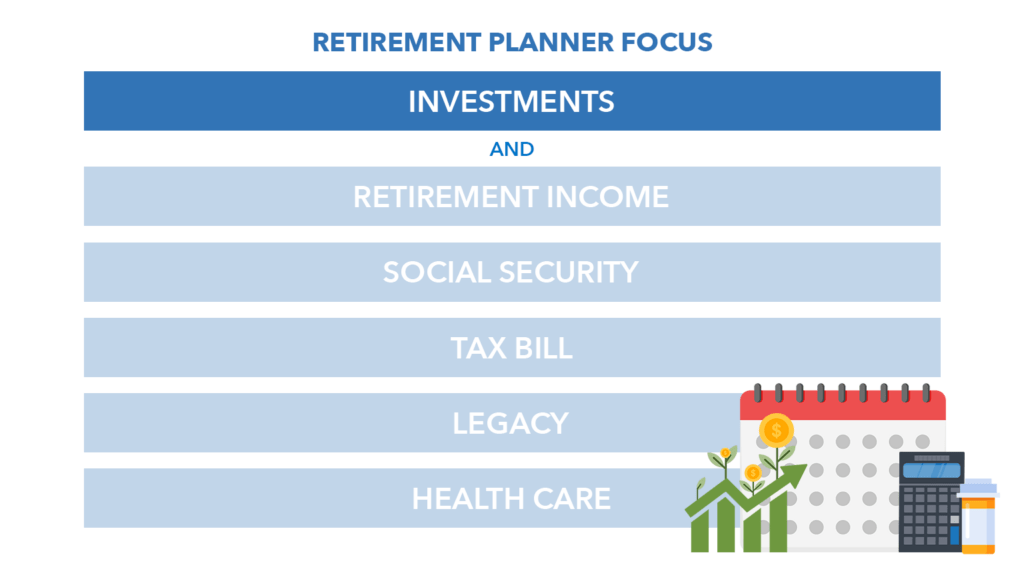
Retirement planning still includes investments, but it also brings together decisions involving income, Social Security, taxes, health care, lifestyle, and legacy.
Clint Huntrods, PhD, Certified Financial Fiduciary®, says the conversations you are having can provide a clue about the type of guidance you are receiving. “Has it been about investments, and that’s kind of where that conversation starts and stops? Well, you’re probably working with an accumulation advisor.”
Moving From Savings to a Written Retirement Plan
Someone can have substantial retirement savings and still not have a written retirement plan.
As retirement approaches, knowing account balances and investment returns does not necessarily answer questions about how much income those accounts can provide, when withdrawals should begin, or how one decision could affect another.
A written plan can provide a way to evaluate those choices.
“The fact that that plan is written on paper, the importance of that should not be overlooked, because there’s so many decisions that you have to make that you’ve never had to make before,” Loren says.
A comprehensive retirement plan can bring those decisions together instead of treating investments, taxes, Social Security, and other retirement considerations separately.
At Merkle Retirement Planning, the written RetireSecure Roadmap is organized around six pillars: lifestyle, income, taxes, investments, health care, and legacy.
Start With the Retirement You Want to Live
Retirement planning is ultimately about more than money. The financial decisions should support the life you want those savings to provide.
That makes lifestyle a logical starting point.
What would an ideal day in retirement look like? Do you plan to travel? Spend more time with family? Pursue hobbies? Move? Volunteer? Work part-time?
Once those goals become clearer, you can begin estimating what that lifestyle could cost. That information helps shape the income plan.
“From a lifestyle perspective, this is where we want to talk to you about what matters to you in retirement,” Clint says.
Retirement planning can help connect the money you have accumulated with the life you want to live.
Turn Retirement Savings Into Retirement Income
During your career, for most people, a paycheck arrives on a regular schedule. Retirement changes that.
Your income may eventually come from several places, including Social Security, IRAs, 401(k)s, pensions, non-retirement investments and cash accounts.
A retirement income plan considers how those sources work together and how much income they may provide at different retirement ages.
For example, a hypothetical projection could show that retiring at age 62 provides $3,000 a month from Social Security and another $4,000 a month from IRAs, non-IRA investments or bank accounts.
“It’s very precise, very specific, and that’s what gives you the clarity as you make those decisions,” Loren says.
The planning doesn’t stop with how much to withdraw. It can also address where withdrawals should come from, how often they should arrive, and how the strategy may need to adapt during periods of market volatility or higher inflation.
Look Beyond This Year’s Tax Return
Taxes are another area where the transition into retirement can change the planning conversation.
Tax preparation generally looks backward at what happened during the previous year. Proactive retirement tax planning looks forward and considers how decisions today could affect taxes years or even decades from now.
That may include evaluating Roth conversions, deciding whether contributions should go to the pre-tax or Roth side of a 401(k), managing highly appreciated stock, and considering how future required distributions could affect taxable income.
The potential dollars involved can be significant.
Loren gives the example of someone with $1 million in pre-tax retirement savings. If retirement income is extrapolated over a 25-year retirement, “Your tax bill, your retirement tax bill could be in excess of $500,000 from that million dollar portfolio.”
That doesn’t mean everyone with $1 million will owe that amount. It illustrates why looking beyond the current year’s taxes can be an important part of retirement planning.
Prepare Investments for a New Job
Investments don’t become less important when you retire. Their job changes.
During the accumulation years, the goal is generally to put money into a portfolio and allow it to grow over time. In retirement, you may begin regularly taking money out.
“Now you’re facing a different challenge, which is taking money out of that portfolio,” Clint says.
That shift can affect how a portfolio is structured and how retirement income is generated during different market environments.
Strategies that made sense while you were accumulating savings may not necessarily be the strategies you want to rely on when those investments are helping provide your paycheck.
Integrate Health Care With the Rest of the Plan
Health care can also affect several other parts of a retirement plan.
Someone retiring before age 65 may need to determine how to bridge the gap between employer-sponsored coverage and Medicare. After Medicare eligibility begins, coverage choices and costs remain part of the equation.
Those decisions shouldn’t necessarily be made independently from income and tax planning.
“One of the most important questions we get around health care is not just what plan is right for me, whether we’re talking about Medicare or other health care options, but how are you going to pay for this health care?” Loren says.
How much taxable income you show in a particular year can also affect certain health care costs, creating another reason to consider the different pieces of a retirement plan together.
Decide What You Want Your Legacy to Look Like
Legacy planning is sometimes viewed simply as deciding who receives your assets after you die. A comprehensive retirement projection can make the conversation broader.
Some people discover that they may leave more behind than they expected. That can prompt an entirely different question: Would they rather use some of that money during retirement?
That could mean retiring earlier, spending more during the early years of retirement or giving differently during their lifetime.
Legacy planning can also work alongside tax and estate planning to consider how assets may eventually transfer to children, charities, or other beneficiaries.
Ask What Happens When One Spouse Dies
For married couples, a retirement plan should also consider what happens financially after the first spouse dies.
The surviving spouse may lose one Social Security benefit. Pension income could decrease depending on the election that was made. Tax filing status also changes.
Loren illustrates the potential tax impact with a married couple in the 12% federal income tax bracket. Their taxable income can be $100,800 for 2026, before reaching the next bracket. The 12% federal income tax bracket for single filers applies to taxable income between $12,401 and $50,400 for 2026.
Meanwhile, household income may not decline proportionately after one spouse dies.
“You could find yourself with maybe two-thirds of the income as what happened when you were both alive, but now your tax rates, instead of 12%, jump up to 22%, depending upon what tax, tax bracket you’re in,” Loren says.
Planning for that possibility while both spouses are alive may provide more options than waiting until the surviving spouse has to make those decisions alone.
Five Questions to Ask About Your Retirement Planning
If you’re approaching retirement and aren’t sure whether your current financial guidance extends beyond investment management, consider whether you can answer these five questions:
- Do I have a written retirement plan?
- How will I decide when to take Social Security?
- What is my long-term tax plan in retirement?
- Do I have a plan for my health care costs in retirement?
- What happens to my income if my spouse dies first?
Having an investment advisor is not inherently better or worse than working with a retirement planner. The more important question is whether the guidance you receive matches the decisions you face during your current phase of life.
As retirement approaches, the focus begins to move beyond how much you’ve accumulated. The next challenge is bringing lifestyle, income, taxes, investments, health care, and legacy together so the savings you’ve spent decades building can support the retirement you’ve been planning for.
—
Watch the full episode on YouTube and learn more about the difference between investment-focused advice and comprehensive retirement planning.
—
This is a hypothetical example used for illustrative purposes only. It is not representative of any specific investment or combination of investments. There is no assurance or certainty that any investment or strategy will be successful in meeting objectives.