Losing a spouse can change more than the emotional landscape of retirement. Social Security benefits, pension income, taxes, and required minimum distributions (RMDs) can all shift. Understanding those changes ahead of time can help couples build a retirement plan designed to support either spouse in the years ahead.
Retirement Can Change Overnight
Most couples spend years preparing for retirement together. They decide when to retire, when to claim Social Security, and how much they expect to spend each month.
But there is another scenario that deserves a place in those conversations: What happens financially when one spouse dies?
The loss itself comes with grief and major life changes. At the same time, the surviving spouse may suddenly be responsible for financial decisions previously handled together.
Loren Merkle, CFP®, RICP®, Certified Financial Fiduciary®, says the combination can quickly become overwhelming. “There’s a lot of emotional trauma that you will be working through. But at the same time, there’s a lot of financial uncertainty that can creep in.”
For many couples, one spouse often takes the lead on household finances. That may mean paying bills, managing investments, monitoring bank accounts, or making retirement decisions. If that spouse dies first, the surviving spouse may be learning those responsibilities while grieving.
That is one reason a retirement plan should be designed for more than the years when both spouses are alive.
As Haley Gutschenritter, CFP®, explains, “We not only have to make sure that these plans work for when both of them are alive, but also when one person passes away.”
When Two Retirement Incomes Become One
Social Security is often one of the first income sources to change after the death of a spouse.
A surviving spouse generally does not continue receiving both Social Security benefits. Instead, the surviving spouse may be eligible to receive the higher benefit.
Pensions can create another significant change. If the pension holder selected a single-life option, the pension payments may end when that person dies.
Meanwhile, many household expenses do not decline at the same rate as income. A mortgage payment or property taxes may remain the same. Utilities, insurance, and other household expenses may change very little.
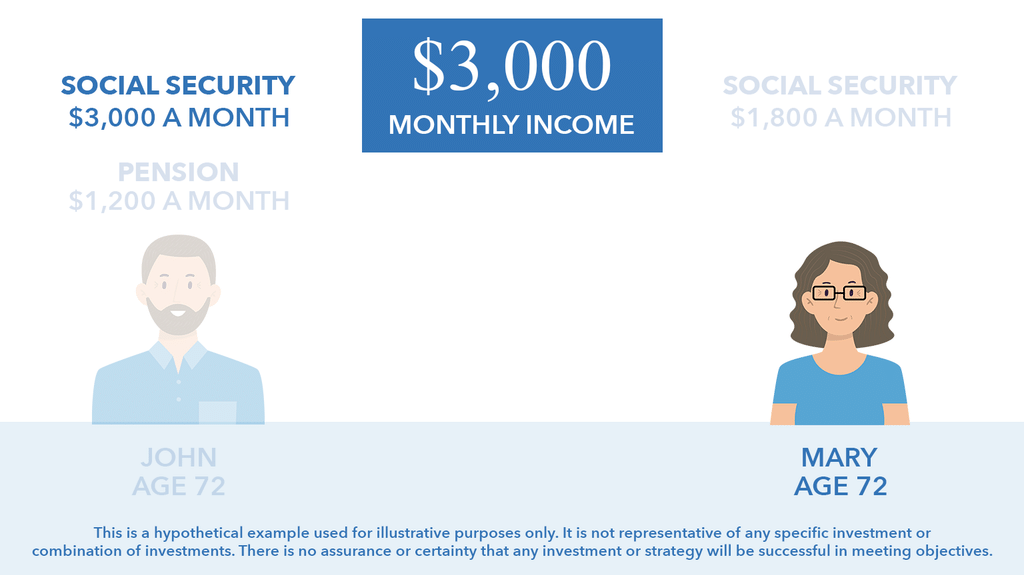
Consider the hypothetical example of John and Mary, both age 72.
Together, they receive $6,000 per month:
- John receives $3,000 per month from Social Security.
- Mary receives $1,800 per month from Social Security.
- John receives a $1,200 monthly pension with no survivor benefit.
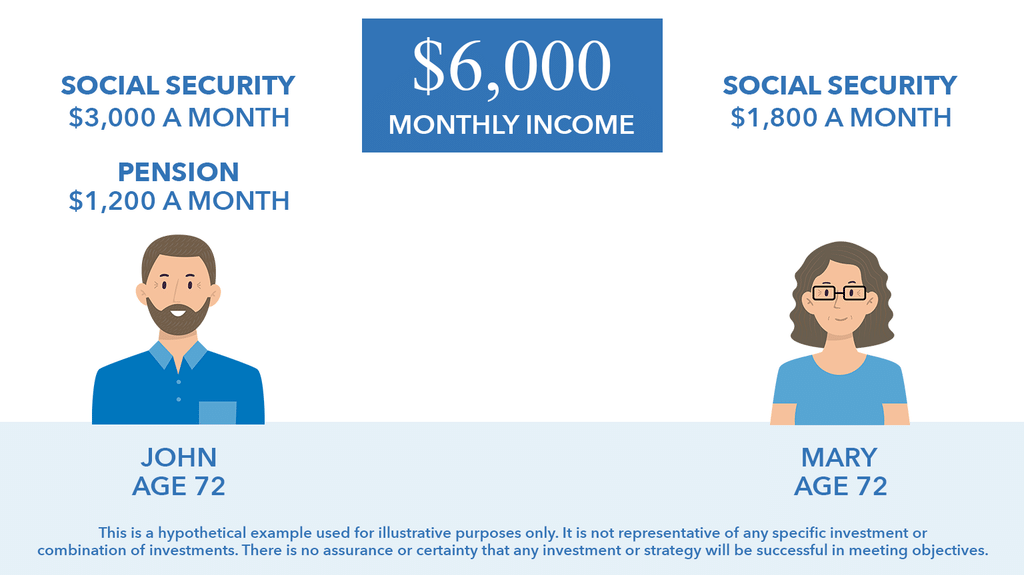
In this hypothetical example, if John dies and Mary qualifies for the survivor benefit described, her own $1,800 benefit would no longer be paid, and she could receive John’s $3,000 benefit instead. John’s $1,200 pension also ends.
Their $6,000 in monthly household income becomes $3,000.
Yet Mary’s mortgage, utilities, insurance, health care, and other expenses may remain relatively similar.
How Taxes Can Change for a Surviving Spouse
Income is only part of the equation. The surviving spouse’s tax situation can change, too.
After the applicable period for filing jointly following a spouse’s death, the survivor generally moves from married filing jointly to single filing status. That means narrower federal income tax brackets and a lower standard deduction.
Loren describes the difference by comparing tax brackets to buckets. A married couple has a larger bucket to fill before income begins spilling into the next tax bracket. For a single filer, that bucket becomes much smaller.
That can create an uncomfortable combination: The surviving spouse may have less household income while a greater portion of that income becomes subject to higher marginal tax rates.
Social Security Decisions Can Affect the Surviving Spouse
A Social Security claiming decision isn’t necessarily just about maximizing income today. For married couples, the decision can also affect the income available to the surviving spouse later.
Haley explains one strategy to consider: “So we (may) want to try to squeeze the most we can out of the smaller benefit while deferring the higher benefit to help maximize the income and protect the surviving spouse.”
Consider another hypothetical example.
Example #1: Suppose the higher-earning spouse claims Social Security at age 62 and receives $2,200 per month. When the higher earner dies, the survivor benefit could be based on $2,200 a month.
Example #2: Now imagine the higher earner instead delays claiming until age 70 and receives $3,800 per month. If that spouse dies later, the survivor benefit could be based on that $3,800 monthly amount instead.
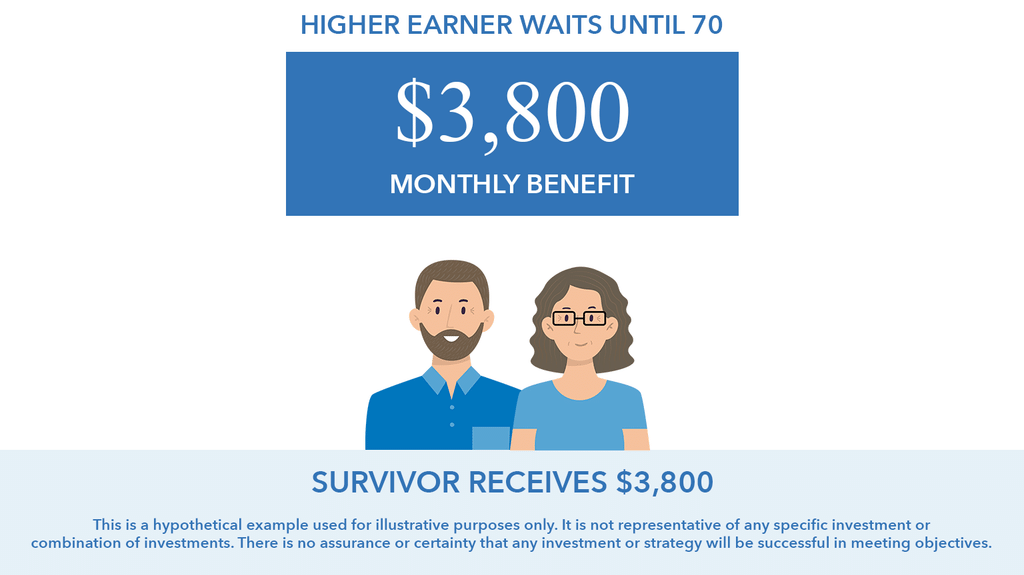
That’s a $1,600 monthly difference in this hypothetical example.
It doesn’t mean delaying until 70 is appropriate for every couple. Available savings, other income, health, longevity considerations, taxes and retirement goals can all influence a Social Security strategy.
The important question is not only what a claiming decision means while both spouses are alive, but what it could mean if either spouse is left managing retirement alone.
Pension Decisions May Be Permanent
Pensions present another decision that can have lasting consequences.
A single-life pension generally provides a larger monthly payment while the pension holder is alive, but payments end at death. A joint-and-survivor option generally provides a smaller monthly benefit but continues some or all of that income for the surviving spouse, depending on the option selected.
“And so that is something that we want to consider any time that we’re electing pensions,” Haley says. She encourages couples to consider the long-term impact the pension decision can have on retirement income.
Consider the hypothetical example of a $3,000 monthly single-life pension compared with a $2,600 monthly pension with a 100% survivor option.
That’s a $400 monthly difference.
For some households, the survivor benefit may be worth that reduction. Other households may have sufficient assets, insurance, or other income to consider a different approach. The important part is understanding what each option means before making an election that may be permanent.
RMDs Can Add Another Tax Challenge
Required minimum distributions (RMDs) can make the tax picture more complicated.
Return to the hypothetical example of John and Mary. At age 72, they may be approaching the age when required minimum distributions begin, depending on their birth years.
If John dies and Mary inherits his IRA, she may eventually be managing required distributions associated with a larger pool of retirement assets while also facing the narrower tax brackets of a single filer.
As Loren explains, “That is stacked on top of her required minimum distribution, but now she has a much more condensed tax bracket.”
That is one reason tax planning during the years when both spouses are alive can matter later. Strategies such as Roth conversions may be worth evaluating during years when a couple has access to the wider married-filing-jointly tax brackets.
The goal isn’t simply to determine this year’s tax bill. It is to consider how decisions today could affect taxes throughout both spouses’ lifetimes.
Medicare Costs Can Change, Too
Taxes aren’t the only expense tied to income.
Income-related monthly adjustment amounts, commonly known as IRMAA, can increase Medicare Part B and Part D costs for people whose income exceeds certain thresholds.
Those thresholds differ depending on filing status. That means a surviving spouse could potentially encounter higher Medicare premiums at a lower household income than when the couple was married.
This is another example of why retirement decisions rarely exist independently. Income decisions can affect taxes. Tax decisions can affect Medicare costs. Social Security and pension decisions can affect the income available to the surviving spouse.
A comprehensive retirement plan considers how those pieces interact.
Five Conversations to Have Before One Spouse Is Left Alone
Preparing for survivorship doesn’t mean trying to predict exactly what will happen. It means understanding the possibilities and making informed decisions while both spouses can participate.
Start with survivor income. Calculate what happens to Social Security, pensions, and investment income if either spouse dies first. Then compare that income with the expenses the surviving spouse could still face.
Next, consider Social Security from both perspectives. What does each claiming strategy provide while both spouses are alive, and what could the survivor receive later?
Review pension elections before retirement, especially when the election cannot be changed after benefits begin.
Tax planning should also include a survivor scenario. Couples can evaluate whether decisions made while filing jointly could help reduce the surviving spouse’s potential tax exposure later.
Finally, both spouses should understand the retirement plan, even if one person normally handles the finances.
“The best thing you could do for your spouse is leave them a plan that they understand,” Haley says.
That includes knowing where accounts are held, how income is generated, where important documents are located, and what decisions have already been made.
A Plan for Both of You
A retirement plan built only around the assumption that both spouses will always be there to manage it together leaves an important question unanswered.
What happens when there is only one?
A survivorship analysis can help couples see how Social Security, pension income, investments, taxes, health care expenses, and legacy decisions could change after the death of either spouse.
Knowing who the surviving spouse can turn to, where the money is located, and how the retirement strategy is designed can be as important as the assets themselves.
The goal isn’t to make an already difficult subject more frightening. It’s to have the conversation while both spouses are there to participate in it and to build a retirement plan designed not just for life together, but for the possibility that one spouse may someday have to carry it forward alone.
Watch the full episode on YouTube and learn more about how losing a spouse can change more than the emotional landscape of retirement.
This is a hypothetical example used for illustrative purposes only. It is not representative of any specific investment or combination of investments. There is no assurance or certainty that any investment or strategy will be successful in meeting objectives.