Retiring before age 65 may feel out of reach, especially when factoring in income, taxes, and health care. This article breaks down seven practical steps to help you understand what it really takes to retire early—and how the right plan can make it possible.
Step 1: Get Clear on the Life You Want to Retire Into
For many people, age 65 becomes the default—not because it’s the goal, but because it feels like the safest option. As Retirement Planner Loren Merkle explains, “It’s not because you want to retire at age 65, but because you feel like you can’t afford health care costs until age 65.”
That’s why the first step isn’t about numbers—it’s about clarity.
Before you can determine if early retirement is possible, you need to define what you’re retiring into. Travel, hobbies, time with family—all of it shapes your future expenses and ultimately your plan. Without that clarity, retirement becomes a guess instead of a decision.
Step 2: Plan for a Longer Retirement Than You Think
Retiring early means your money has to last longer—sometimes much longer.
A retirement that begins in your late 50s could stretch 30 or even 40 years. That’s why longevity planning is critical. As Retirement Planner Chawn Honkomp says, “we need to start thinking about the longevity of at least one of you, if not both.”
This step isn’t about predicting the future perfectly—it’s about preparing for it responsibly. That includes factoring in inflation, evolving spending patterns, and the different phases of retirement.
Step 3: Determine What “Enough” Really Means
“How much do I need?” is the question everyone asks—and the answer is rarely simple.
As Loren puts it, “it is the number one question, how much is enough for me to retire and live the retirement I want?”
Many people turn to rules of thumb for guidance, but those can be misleading. Chawn cautions, “that is not customized to your scenario. It’s a very generic statement.”
The reality is that retirement income isn’t one-size-fits-all. Your spending, income sources, and goals will dictate what “enough” looks like—and that number may be very different from what you’ve seen online.
Step 4: Increase Your Savings Power (Without Feeling Deprived)
If early retirement is the goal, the last few working years become incredibly valuable.
This is the time to be intentional, maximizing your 401(k), evaluating tax strategies, and making decisions about where your dollars go. Even small adjustments can make a meaningful difference over time.
One example is how you use an HSA. Letting those dollars grow while you cover current expenses out of pocket can create a dedicated, tax-advantaged pool for future health care needs.
And building Roth assets adds flexibility. As Chawn explains, “the more Roth dollars that anyone can accumulate… it creates more options and more control later in life.”
Step 5: Use the Right Buckets for the Right Time
One of the biggest concerns about retiring early is market risk—especially right before or after you retire.
That’s where structure comes in.
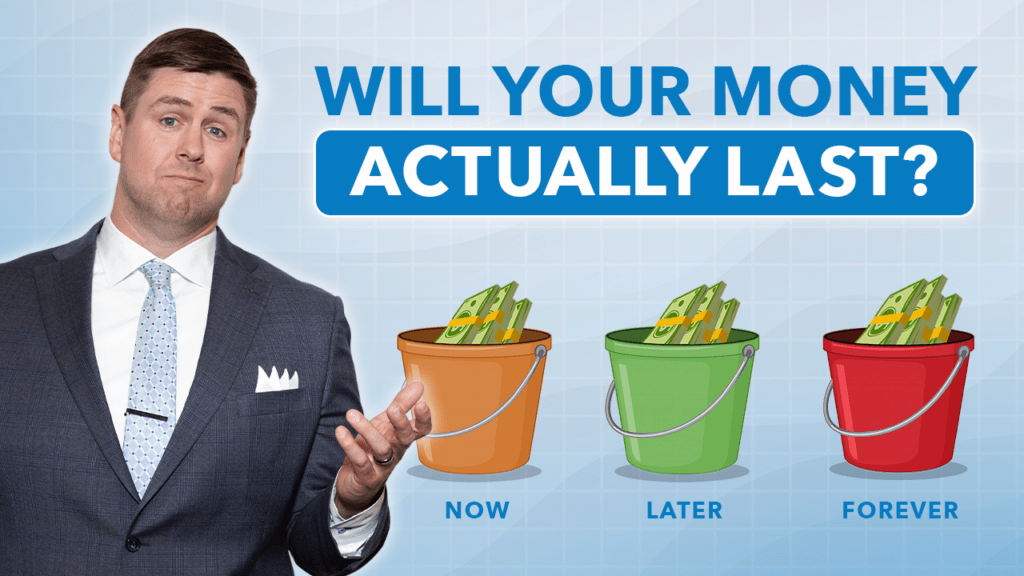
Loren describes a strategy built around different time horizons: “you have the now bucket… the later bucket… and then you have the forever bucket.”
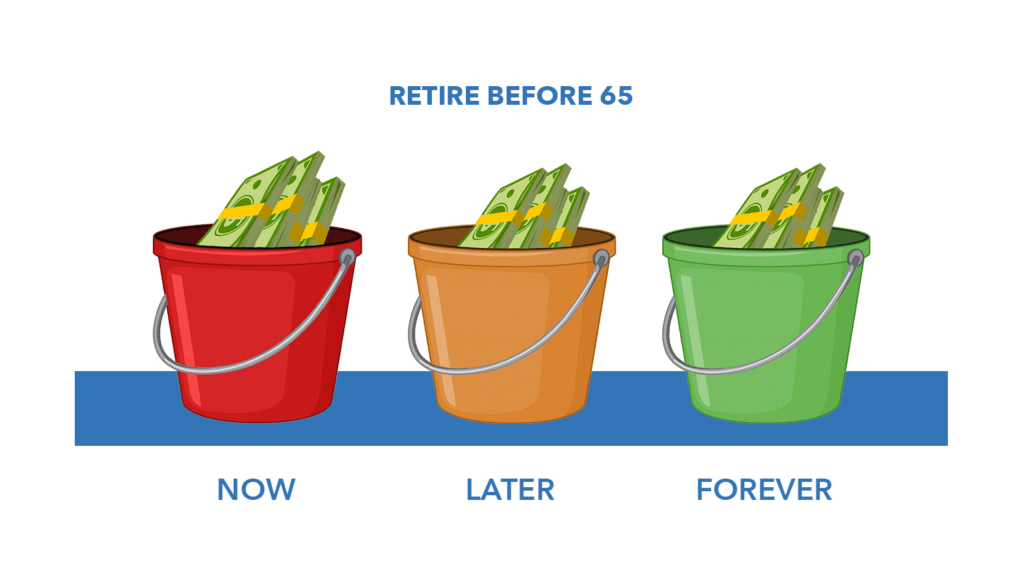
Each bucket serves a purpose. Short-term income needs are protected, while longer-term dollars remain positioned for growth.
This approach can help create confidence—because your immediate income isn’t dependent on what the market does next.
Step 6: Adjust Your Investment Strategy for the Transition
The transition into retirement isn’t just about stopping work—it’s about shifting how your money works.
As Chawn explains, “the same investments that got people to 55 or 60… aren’t necessarily the same investments that are going to get you through retirement as well.”
During your working years, you’re contributing and growing assets. In retirement, you’re withdrawing and relying on them.
That shift requires a different approach to risk, income, and overall portfolio design—especially if your retirement timeline is longer.
Step 7: Solve the Two Big Gaps: Taxes and Health Care
For many, these are the two biggest barriers to retiring before 65.
Health care often drives the retirement timeline, but there are more options available than some people realize. The key is understanding the cost and how it fits into your plan.
Taxes are just as important—if not more. As Chawn points out, “for most of you, the expense category of your tax bill is going to be your single largest expense.”
A thoughtful tax strategy can help reduce that burden over time, keeping more of your money aligned with your retirement vision.
What It All Means
Retiring before 65 isn’t about cutting corners or taking big risks—it’s about making informed, intentional decisions.
Early retirement isn’t automatic. But with thoughtful steps—and a retirement plan that brings everything together—it may become more achievable than many people realize.
Watch the full episode on YouTube and learn more about what it really takes to retire early—and how the right plan can make it possible.