For many, the 401(k) represents a large portion of retirement savings, so understanding your options—and the nuances that come with them—is an important part of your retirement income plan. We’ll break down the main paths you can take with your 401(k) upon retirement and the considerations to keep in mind, based on insights from Retirement Planners Loren Merkle and Clint Huntrods.
–––––––––––––––––––––––––––––––––––––––––––––––––––––––––––––––––––––––––––––––––––––––––––––
The 401(k): A foundational Retirement Tool
401(k) accounts are employer-sponsored retirement accounts with multiple benefits. You can contribute more to a 401(k) than to most other retirement accounts, and if you’re 50 or older, the annual limit rises even higher. These contributions can go in pre-tax (meaning you defer taxes until withdrawal) or post-tax (Roth 401(k)), allowing them to grow either tax-deferred or tax-free, respectively.
Option 1: Leaving Your Money in the 401(k) Plan
One of the default options is to simply leave your money in your former employer’s 401(k) after you retire. Your investments remain as they are, and, typically, you can begin taking withdrawals at age 59½.
However, as Clint explains, these plans are primarily designed for accumulation, not for managing retirement income distributions. If you’re hoping to get more flexible or strategic with your income and tax planning, your 401(k) may not offer that versatility.
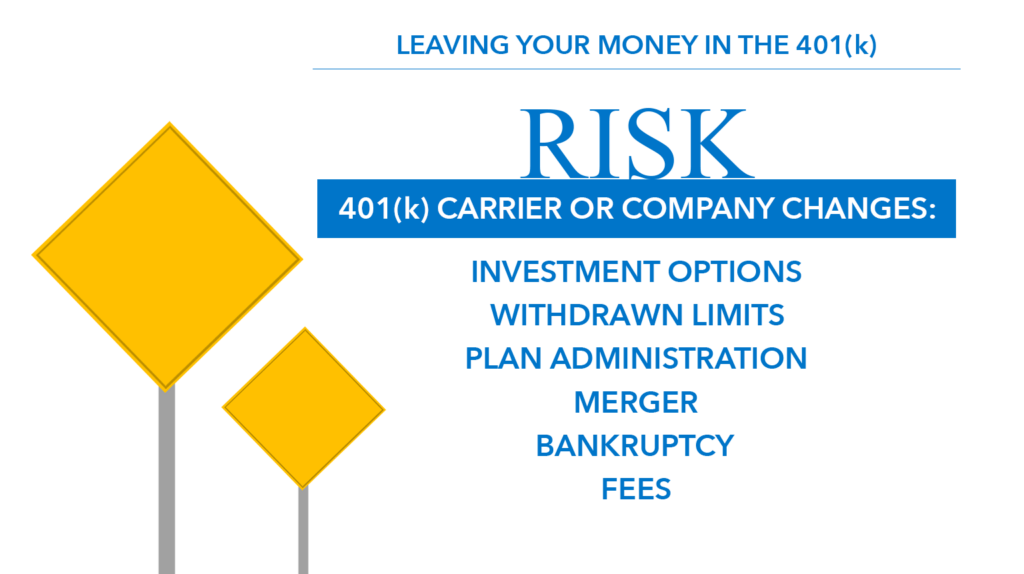
Another consideration: Employers can change plan administrators or rules, switch investment options, adjust withdrawal limits, or experience corporate events like mergers or bankruptcies. Any of these can impact your account without much warning.
Yet, there are cases where leaving funds in a 401(k) is beneficial. Loren points out that if you separate from your employer at age 55 or older, you can access your 401(k) funds penalty-free before reaching 59½—an option not available with IRAs. This can be a key benefit for those planning an early retirement.
Option 2: Rolling Your 401(k) Into an IRA
Transferring your 401(k) funds to an Individual Retirement Account (IRA) is a strategy to consider. An IRA typically offers a wider array of investment choices, potentially lower fees, and more control over your withdrawal and tax-planning strategies. This consolidation can also simplify your financial life—Loren notes that having funds in a single account (as opposed to several 401(k)s from past employers) streamlines both management and Required Minimum Distributions (RMDs) once you reach the appropriate age.
It’s important to pay close attention to the transfer process. There are two ways to roll over your 401(k) to an IRA: a direct rollover, where funds move straight from your plan to your IRA (usually the best option, as it avoids mandatory tax withholding and IRS penalties), and an indirect rollover, where you receive the money and must deposit it into your IRA within 60 days. The latter has more rules—including a once-per-year limit and a mandatory 20% tax withholding—which can catch retirees unaware.
Keep in mind that once your funds are in an IRA, you usually cannot take penalty-free withdrawals until age 59½, except for a few specific exceptions. If you anticipate needing to access your retirement savings before that age, this is important to factor into your decision.
More Investment Choices – And Tax Flexibility
Inside an IRA, you’re no longer limited to the selection of mutual funds in most 401(k) plans. You’ll have a much broader investment universe, making it possible to fine-tune your portfolio for your retirement income needs and risk tolerance.
Tax Withholding Differences: IRA vs. 401(k)
401(k) Withdrawals:
- Mandatory Federal Withholding: When you take a distribution from a traditional 401(k), the IRS requires 20% federal income tax withholding if it’s an eligible rollover distribution or a lump-sum payment. This happens regardless of your actual tax rate.
- State Withholding: Some states may also require withholding on 401(k) distributions.
- Less Flexibility: You typically can’t opt out of the 20% withholding, which limits your control over tax planning and cash flow.
IRA WithDrawals:
- More Flexible Withholding: For traditional IRAs, the default federal withholding is 10%, but you can:
- Elect to have no withholding, or
- Choose a different percentage, which can help fine-tune your tax strategy.
- State Withholding: May still apply, depending on your state, but you often have some choice there too.
- More Control: This flexibility lets you align your withdrawals with other income sources, avoid over- or under-withholding, and potentially reduce quarterly tax payments or a large tax bill in April.
- Roth Conversion Opportunity: Another advantage of IRAs is the ability to convert traditional IRA assets to a Roth IRA. While you’ll owe income tax on the amount converted in the year of the conversion, future growth inside the Roth IRA is tax-free, and qualified withdrawals (after age 59½ and the five-year holding rule) are also tax-free. This strategy can be especially powerful for retirees in a lower tax bracket now than they expect to be in the future, allowing them to shift assets into a more tax-efficient account for the long run.
The Bigger Picture: Your Retirement Plan
As both Clint and Loren emphasize, your 401(k) is just a piece of the puzzle. For families and individuals approaching retirement, it’s wise to take stock of your 401(k) and start integrating it into your broader plan five to ten years before your intended retirement date. This proactive approach leaves plenty of time to adjust investments, consider rollovers, and ensure your withdrawal strategies serve your needs.
Click here to watch the full episode “What To Do With Your 401(k) in Retirement” on YouTube!