Annuities are one of the most discussed—and often misunderstood—retirement planning tools. This blog explains what annuities are, the different types available, their potential benefits and drawbacks, and how to determine whether an annuity belongs in your overall retirement plan.
Why Annuities Can Cause So Much Confusion
Few retirement planning topics generate as much confusion as annuities. Part of the challenge is that there isn’t just one type of annuity. There are numerous variations, each with different features, guarantees, costs, and restrictions.
As Retirement Planner Loren Merkle explained, “Often misunderstood because there’s so many of them, and many of these annuities come with contracts with not really common language.”
That complexity makes it important to understand exactly what role an annuity is supposed to play before purchasing one.
Loren emphasized that “you need to look at your plan” and “make sure it fulfills that purpose.”
Annuity 101: What Is an Annuity?
At its core, an annuity is an insurance product. You provide a premium to an insurance company, and in return the company offers certain guarantees, benefits, or income options.
Retirement Planner Clint Huntrods described it this way: “An annuity is really an insurance strategy.”
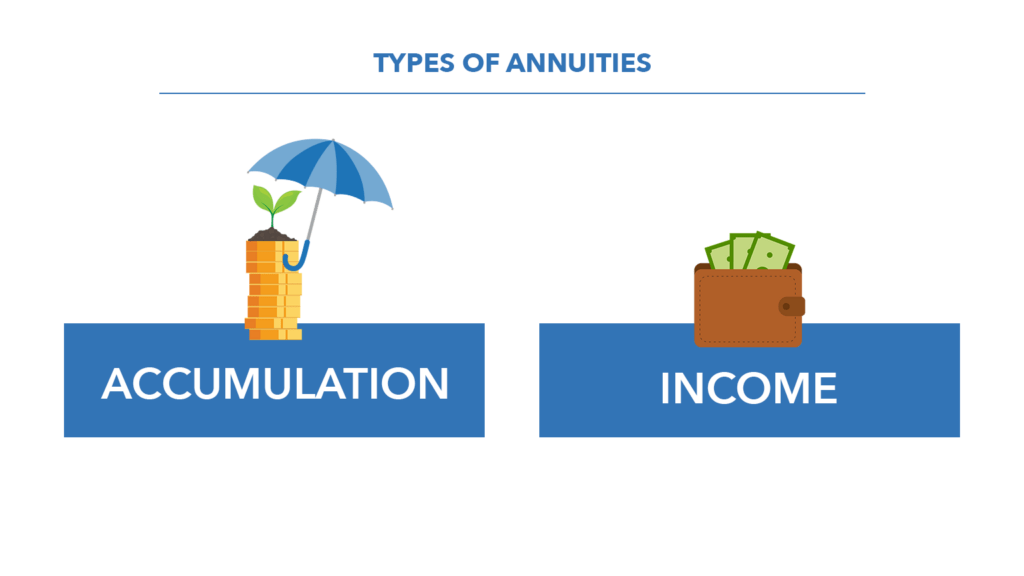
Generally, annuities fall into two broad categories:
- Accumulation annuities, designed to help grow assets over time.
- Income annuities, designed to create a future income stream.
While the categories are simple, the products inside those categories can vary significantly.
The Two Main Purposes of Annuities
Accumulation: Growth With Protection
Many retirees want a portion of their portfolio to participate in growth without experiencing the full ups and downs of the stock market.
According to Clint, people often use accumulation annuities because “you’re looking for some growth” while also seeking “safety.”
One common option is a fixed indexed annuity. These products are designed to provide some protection during market downturns while still allowing participation in market gains.
For retirees concerned about volatility, this can offer a middle ground between traditional market investments and conservative savings vehicles.
Income: Creating a Personal Pension
Other annuities are built specifically to generate income.
Some begin payments immediately. Others allow assets to grow before the income stream starts later in retirement.
For retirees who do not have a traditional pension, an income annuity can help create a predictable monthly paycheck.
As Loren noted, “Some of the most financially confident retirees have a pension.” Since fewer workers retire with pensions today, many choose to create “their own personal pension through an income annuity.”
The Potential Benefits of Annuities
Guaranteed Income
One of the biggest attractions of certain income annuities is their potential to provide income for as long as the contract terms allow. Guarantees are backed by the claims-paying ability of the issuing insurance company.
Loren provided a hypothetical example: “Instead of just a $2,500 a month Social Security payment, you’re going to get $5,000 a month, $2,500 from Social Security, $2,500 from your annuity.”
For many retirees, that type of predictability can provide peace of mind.
Reduced Market Stress
Retirement often changes how people think about investment risk. When you’re no longer earning a paycheck, large market swings can feel much more personal.
Clint explained that many retirees “don’t want to be pedal to the metal from a market risk standpoint.”
A protected annuity strategy may help reduce portfolio volatility while still providing opportunities for growth.
Longevity Protection
People are living longer than previous generations, which means retirement savings may need to last 30 years or more.
Clint pointed out that a guaranteed income stream “that’s going to provide you income as long as you’re alive could make an awful lot of sense long-term.”
The Drawbacks Retirees Should Understand
Complexity
Annuities often include riders, income features, participation rates, caps, and other contract provisions that can be difficult to understand.
Not every annuity works the same way, making it essential to review the details before making a decision.
Costs
Costs vary widely depending on the product.
Variable annuities, in particular, may include mortality expenses, investment management fees, and optional rider costs.
Loren noted that it is “not uncommon for you to pay somewhere between 3% to 5% per year” in certain variable annuity arrangements.
While newer annuity options may have lower costs, understanding fees remains critical.
Liquidity Restrictions
Most annuities limit how much money can be withdrawn during the surrender period.
Loren explained that many contracts include “a seven to 10 year surrender penalty timeframe.”
That means withdrawing too much money too soon could result in significant penalties.
For this reason, annuities generally work best as part of a diversified retirement strategy rather than as the home for all of a retiree’s assets.
When an Annuity May Make Sense
An annuity may deserve consideration if:
- You want additional guaranteed income beyond Social Security.
- You do not have a pension.
- Market volatility causes significant stress.
- You value predictable income and stability.
- Longevity runs in your family.
- You need a specific solution for a clearly defined planning goal.
In these situations, an annuity may help fill a gap that traditional investments alone cannot address.
When an Annuity May Not Make Sense
An annuity may be less appropriate when:
- You need maximum liquidity and access to your money.
- You already own an older annuity that no longer fits your goals.
- The product is being presented as a substitute for comprehensive retirement planning.
- You have not yet built a retirement plan that identifies a need for the annuity.
In many cases, the decision should start with the retirement plan, not the product. Understanding your income needs, investment strategy, tax situation, health care considerations, and legacy goals can help determine whether an annuity may fit into your overall plan.
The Plan Comes First
Whether an annuity ultimately belongs in your portfolio depends on your unique retirement goals, income needs, taxes, investments, health care considerations, and legacy objectives.
As Loren explained, “The plan is going to tell you, does an annuity make sense, does an annuity not make sense.”
For some retirees, an annuity can be a valuable tool that provides income, protection, and confidence. For others, different strategies may be a better fit. The key is understanding how the product fits into a comprehensive retirement plan before making a decision.
Watch the full episode on YouTube and learn more about how to determine whether an annuity belongs in your overall retirement plan.
Guarantees are backed by the claims-paying ability of the issuing insurance company.
We are an independent financial services firm helping individuals create retirement strategies using a variety of investment and insurance products to custom suit their needs and objectives. The content and examples shared are for informational purposes only and should not be construed as investment advice or serve as the sole basis for making financial decisions. Individuals are encouraged to consult with a qualified professional before making any decisions about their personal financial situation. Investment Advisory Services offered through Elite Retirement Planning, LLC. Insurance Services offered through MRP Insurance, LLC.