Retirement can change where your income comes from, how that income is taxed, and the tax decisions you could face along the way. A long-term tax plan can help you look beyond this year’s tax bill and consider how Roth conversions, required minimum distributions (RMDs), and different retirement accounts could affect your taxes throughout retirement.
Retirement Changes the Tax Conversation
For decades, saving for retirement can feel relatively straightforward. You contribute to a 401(k), IRA, or other retirement account, invest the money, and watch your balance grow.
Then retirement gets closer, and the questions change.
When should you take Social Security? Which accounts should you withdraw from first? How much should you withdraw? Should you consider a Roth conversion? What happens when required minimum distributions begin?
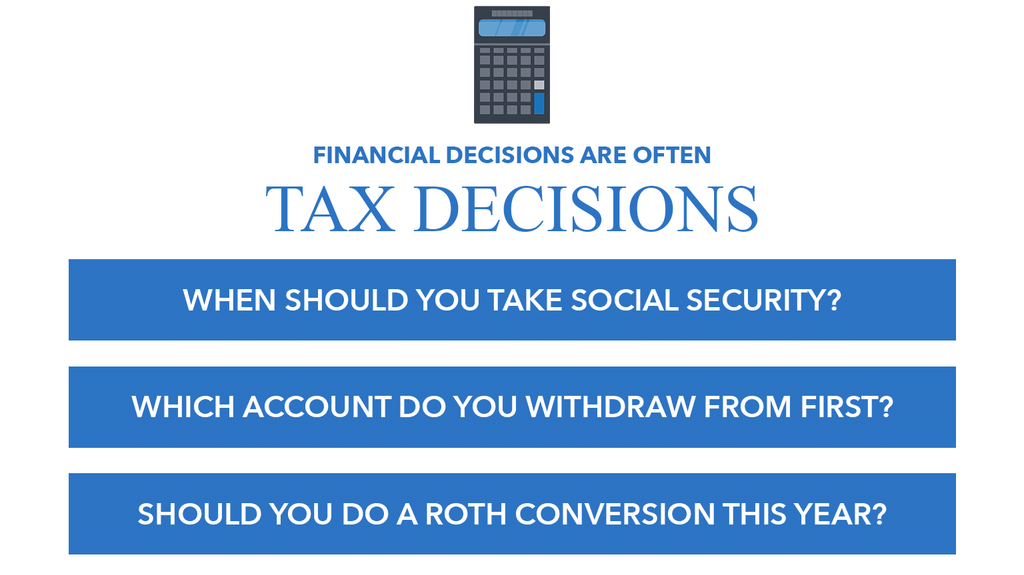
Each decision can have tax consequences.
As Loren Merkle, CFP®, RICP®, Certified Financial Fiduciary®, explains, “Not making a decision is also a tax decision, and that is, in fact, how a lot of this money gets left on the table, by people neglecting the notion of incorporating a tax plan for a variety of reasons.”
That is one reason retirement tax planning is different from simply preparing a tax return. Tax preparation generally looks backward at what already happened. Retirement tax planning looks forward at how decisions today could affect taxes several years or even decades from now.
Why Required Minimum Distributions Matter Before They Begin
Required minimum distributions, or RMDs, may not feel particularly urgent to someone retiring in their early or mid-60s. Depending on your birth year, current law generally requires RMDs to begin at age 73 or 75.
But waiting until RMDs begin to think about them could mean overlooking an important planning window.
Money contributed to a traditional 401(k) or IRA generally received favorable tax treatment when it went into the account and grew tax-deferred. Eventually, taxes become due when that money is withdrawn.
Once RMDs begin, you generally must withdraw a calculated amount from certain retirement accounts each year. The amount can change from year to year based on factors including your account balance and age.
That can create a very different tax picture later in retirement.
A Hypothetical $136,000 Difference
Consider Sue, a hypothetical retiree used to illustrate how looking ahead could affect a retirement tax strategy.
Sue retires at age 65. Between Social Security and the additional investment income she needs to support her lifestyle, the assumptions used in this example place her initially in the 12% federal income tax bracket.
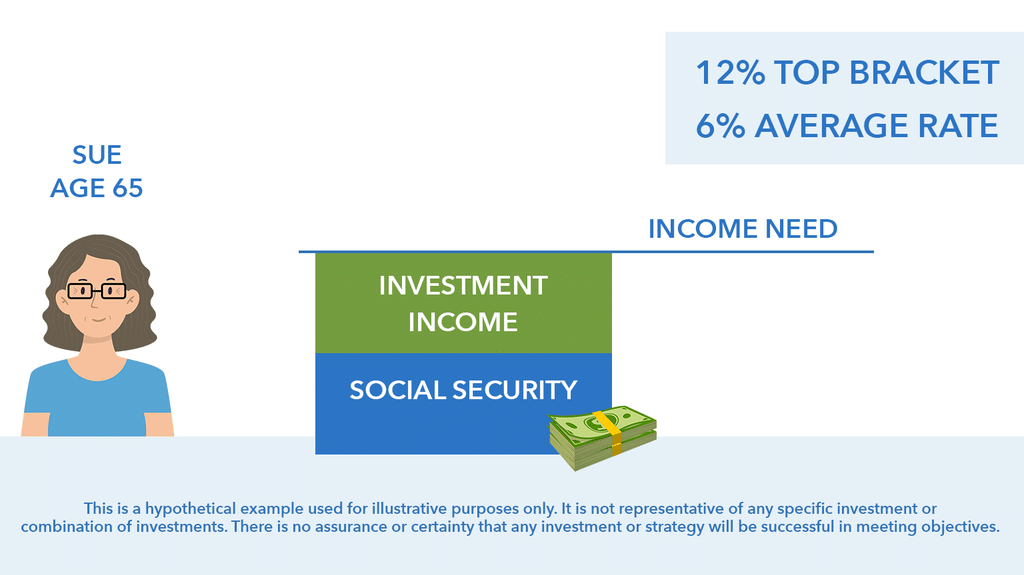
If Sue makes no Roth conversions and her investments grow according to the assumptions used in this hypothetical, her projected required minimum distribution (RMD) at age 75 is approximately $101,000 a year. Under the assumptions used in the example, that additional taxable income places her in the 24% federal income tax bracket.
By age 85, Sue’s projected RMD is approximately $142,000 a year, even though her lifestyle expenses may have slowed.
Under this hypothetical scenario, Sue’s projected cumulative retirement tax bill is approximately $891,000.
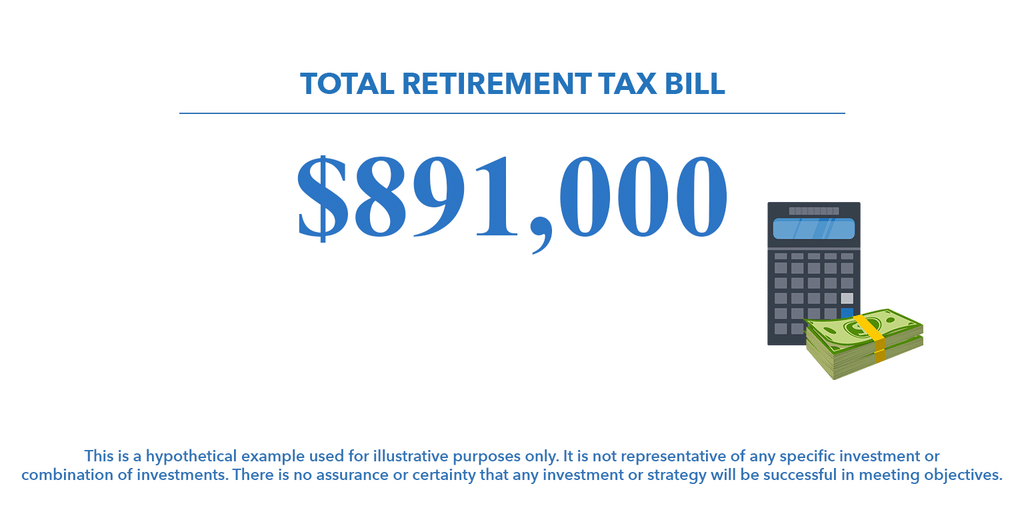
But what could the projections look like if Sue considers Roth conversions beginning at age 65?
In the alternative hypothetical scenario, Sue converts $30,000 per year from her pre-tax retirement savings to a Roth account between ages 65 and 75. Under the assumptions used in the example, those conversions mean paying more in taxes earlier and moving slightly into the 22% federal income tax bracket during those years.
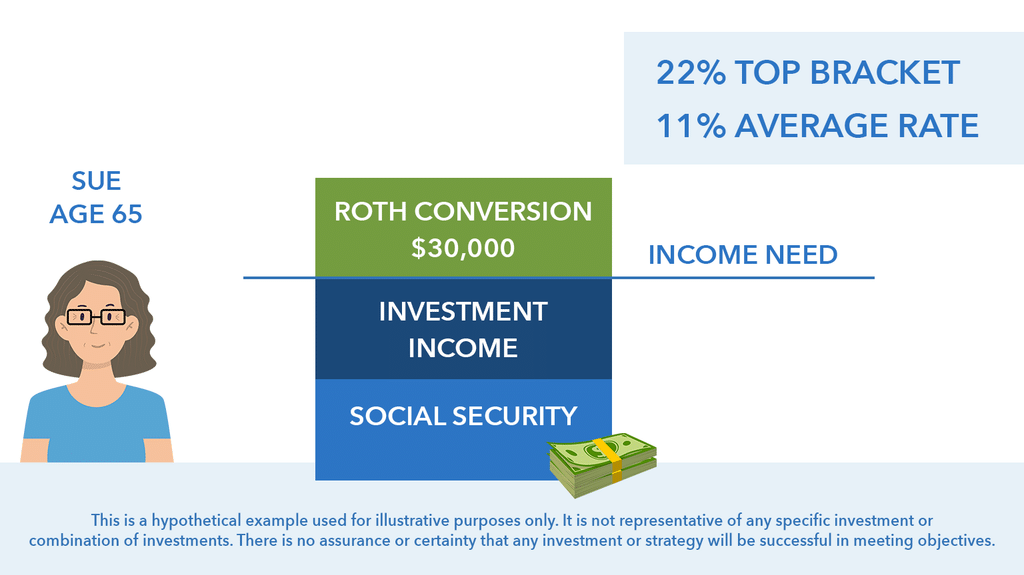
The goal is not simply to minimize this year’s taxes. Instead, the example illustrates how someone might consider whether paying taxes at one rate today could potentially affect the taxes they pay later in retirement.
Clint Huntrods, PhD, Certified Financial Fiduciary®, explains the trade-off: “What we show is, let’s just say she’s going to do $30,000 per year of a Roth conversion. And when she does that, now at age 65, she would push herself up slightly into the 22% tax bracket, but what we find is that 22% now is better than 24% somewhere down the road.”
Under the assumptions used in this alternative hypothetical scenario, Sue’s projected RMD at age 75 is approximately $81,000, compared with approximately $101,000 in the first scenario. At age 85, her projected RMD is approximately $113,000, compared with approximately $142,000.
Her projected cumulative retirement tax bill is approximately $755,000, compared with approximately $891,000 in the first scenario.
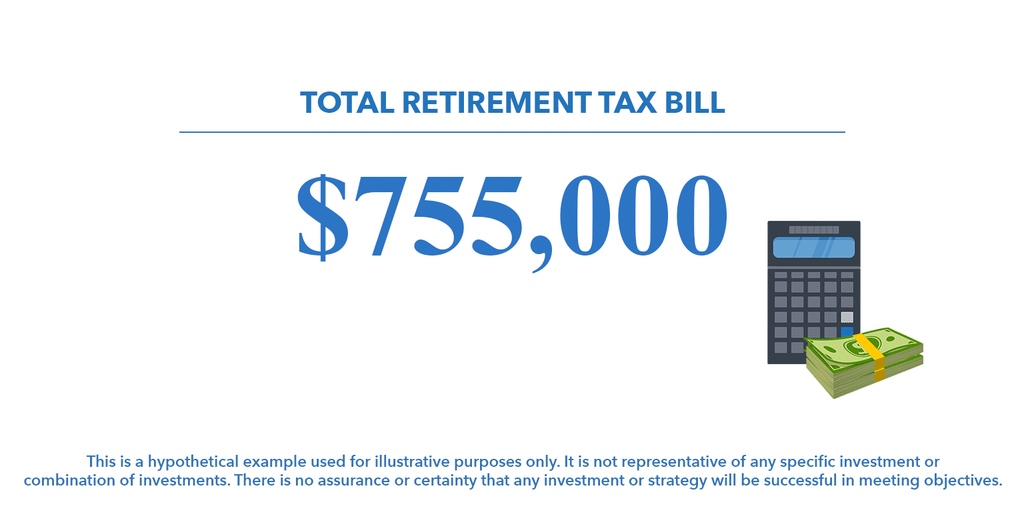
That represents a hypothetical difference of approximately $136,000 over the course of Sue’s retirement.
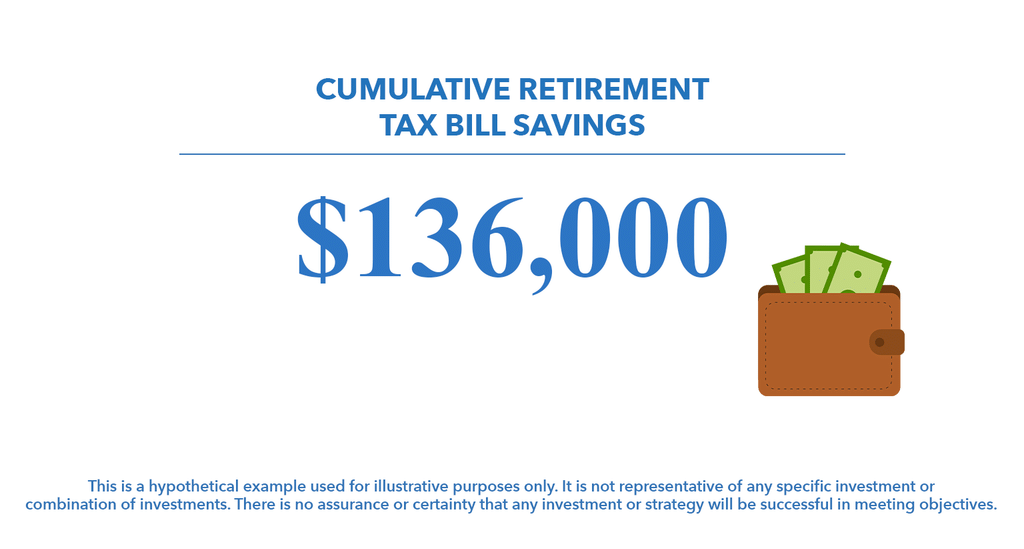
This example is for illustrative purposes only. It is not intended to suggest that everyone should convert $30,000 per year or that Roth conversions will result in tax savings. Instead, it illustrates how looking beyond this year’s tax bill and considering different scenarios may help someone evaluate tax decisions throughout retirement.
The Lowest Tax Bill Today May Not Be the Goal
Sue faces an interesting decision at age 65.
After retiring from her higher-earning working years, she suddenly finds herself in a relatively low tax bracket. It could be tempting to enjoy that lower rate for as long as possible.
Loren describes why that can make the decision difficult: “And she could have coasted in that 12% tax bracket for a number of years, all the way up until age 75.”
But Sue’s tax picture at 65 is only one part of her retirement.
A long-term plan can model what taxes may look like at 70, 75, 80, and beyond. It can also compare what could happen if she takes action with what could happen if she does nothing.
That broader view can help turn the question from “How little tax can I pay this year?” into “How could the decisions I make this year affect my taxes throughout retirement?”
Roth Conversions Are Not One-Size-Fits-All
The hypothetical example shows a significant potential benefit from Roth conversions, but that does not mean the strategy makes sense for everyone or even for the same person every year.
Someone who is still working and earning a high income at age 62 may reach a very different conclusion than that same person at 65 after retiring.
Marriage, income needs, account balances, tax legislation, and lifestyle changes can all affect the calculation.
Clint explains, “It’s not necessarily that a Roth conversion each and every year makes sense for everyone by any means.”
Even when a conversion makes sense, the amount matters. The decision may need to be reevaluated each year as income, spending, and tax laws change.
Tax Diversification Can Provide More Choices
Many retirement savers are familiar with investment diversification. Tax diversification may be less familiar.
The idea is to have retirement savings in accounts that are taxed in different ways. Traditional 401(k)s and IRAs are generally taxed when money is withdrawn. Qualified distributions from Roth accounts are generally tax-free. Taxable brokerage accounts have their own tax treatment.
Having money in different types of accounts may give you more choices when deciding where your retirement income comes from.
As Clint explains, “But if you have these different buckets of money that are taxed differently, now you can take income from this one, you can take a little income from this one, a little income from this one, be taxed differently.”
Those choices may be useful when considering taxable income alongside other retirement decisions.
Your Retirement Accounts Are Only Part of the Plan
Taxes do not exist in isolation.
A decision about how much to withdraw from an account can affect income. A Roth conversion can affect taxable income. Taxable income can affect other areas of a retirement plan. Social Security decisions can have their own tax implications.
That is why a retirement plan can be more useful when lifestyle, income, taxes, investments, health care, and legacy are considered together.
Loren explains, “And the six pillars of the overall plan, we call this plan the RetireSecure Roadmap. The first pillar is the lifestyle pillar.”
Lifestyle is ultimately what the other pieces are designed to support. Retirement savings are there to fund the travel, hobbies, family time, and everyday life you spent years preparing to enjoy.
A tax plan is not simply about paying the smallest tax bill possible in a single year. It is about understanding the choices available to you and considering how decisions today could affect your taxes throughout retirement.
Looking ahead may give you more time to evaluate those choices before required minimum distributions (RMDs) and other changes become part of your retirement tax picture.
Watch the full episode on YouTube and learn more about how retirement can change where your income comes from, how that income is taxed, and the tax decisions you could face along the way.
Tax Disclaimer (IRS Circular 230) To comply with IRS regulations, we are informing you of the following: Merkle Retirement Planning, LLC and Elite Retirement Planning, LLC, and their representatives do not give tax or legal advice. Any discussion or advice regarding tax issues contained in this document is not intended or written to be used, to avoid taxpayer penalties. Such discussion or advice was written to support the promotion or marketing of the transaction(s) or matter(s) contained in this document. Anyone reading this document or contemplating a transaction discussed in this material should seek advice based on the client’s particular circumstances from an independent tax advisor or an independent attorney.