Estate planning decisions that seem simple today can create unexpected taxes, delays, and loss of control later. Here are four common mistakes to watch for, along with steps to help make sure your assets ultimately go where you intend.
—
Estate planning is often driven by good intentions. You want to make things easier for your family, avoid unnecessary complications, and make sure the assets you spent a lifetime building reach the people you care about.
But sometimes a decision intended to simplify an estate can have the opposite effect.
Loren Merkle, CFP®, RICP®, Certified Financial Fiduciary®, has seen what can happen when those decisions do not work as planned. “There’s not too many months that go by that we don’t see some kind of mistakes take place.”
The consequences can include unexpected taxes, assets going to the wrong person, loss of control, and delays at an already difficult time.
Chawn Honkomp, CFP®, RICP®, CPA, Certified Financial Fiduciary®, says having estate planning documents is only part of the process. “It’s really important to understand how this will actually happen. What will this look like? What does the execution of this estate plan actually look like in the future?”
Here are four estate planning mistakes and how to avoid them.
Mistake #1: Adding a child’s name to the home deed to make the transfer easier
Putting an adult child on the deed to your home may seem like an easy way to transfer the property after your death and potentially avoid probate. But doing so can create tax consequences.
Consider this hypothetical example. Parents bought a home for $100,000 in 1990. Years later, they added their adult son, Charlie, to the deed, making him a 50% owner.
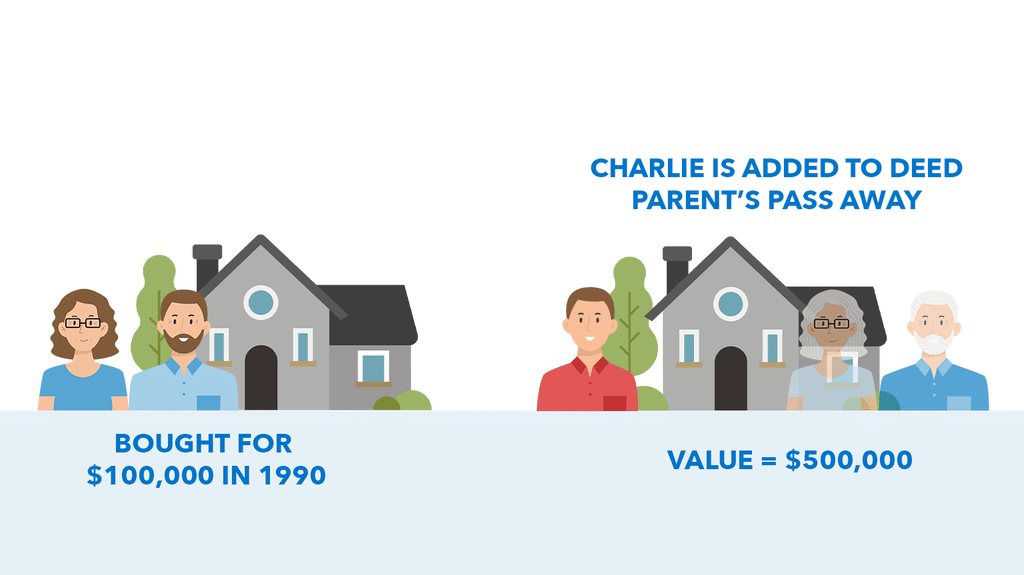
When the parents died, the home was worth $500,000. Because Charlie was added to the deed during his parents’ lifetimes, the tax treatment of his ownership interest could differ from what it might have been if he had inherited the home after their deaths.
For illustration, assume Charlie’s portion of the home has $200,000 in taxable gain when the property is sold. At a hypothetical 15% capital gains tax rate, that could result in approximately $30,000 in federal capital gains taxes. The actual tax consequences would depend on factors such as the property’s cost basis, how ownership was transferred, applicable tax laws, and Charlie’s individual circumstances.
If Charlie had instead inherited the home after his parents died, he may have received different tax treatment because inherited property may qualify for a step-up in cost basis.
How Charlie uses the home afterward could also affect the tax outcome. For example, if he inherited a home valued at $500,000 and later sold it for $600,000, the $100,000 increase in value after inheritance could have tax implications. Different rules may apply if he makes the home his primary residence.
Rather than automatically adding a child as an owner, families may want to consider how different ownership and estate-planning strategies could affect the transfer. Depending on the family’s circumstances and estate plan, maintaining ownership during the parents’ lifetimes or using a trust may be options to discuss with qualified legal and tax professionals.
Mistake #2: Outdated or wrong beneficiary designations on retirement accounts
Your will is not the only document determining who receives your assets.
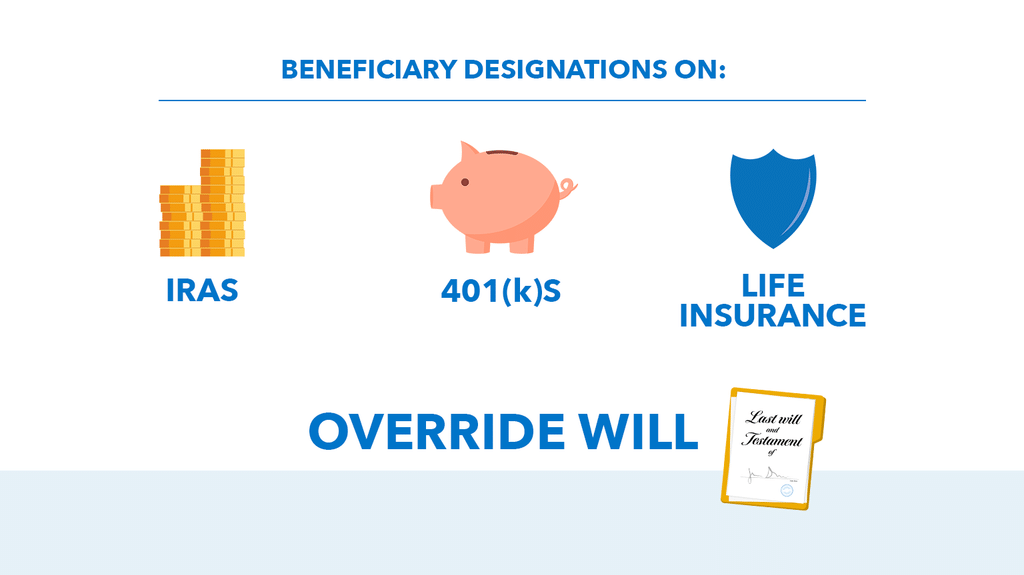
Beneficiary designations on accounts such as IRAs, 401(k)s, and life insurance can supersede instructions in a will. That makes keeping those designations current an important part of estate planning.
Consider someone who names a spouse as the beneficiary of a 401(k), later divorces and forgets to update the account. That person remarries and remains married for another 22 years but never changes the original beneficiary designation.
If the account owner dies with the former spouse still listed as beneficiary, that outdated designation could have significant consequences.
Life changes. People marry, divorce, have children, adopt children, and lose loved ones. Employers may also move their retirement plans from one custodian to another, and beneficiary information may not always move with the account.
That is why beneficiary designations should not be treated as a one-time decision.
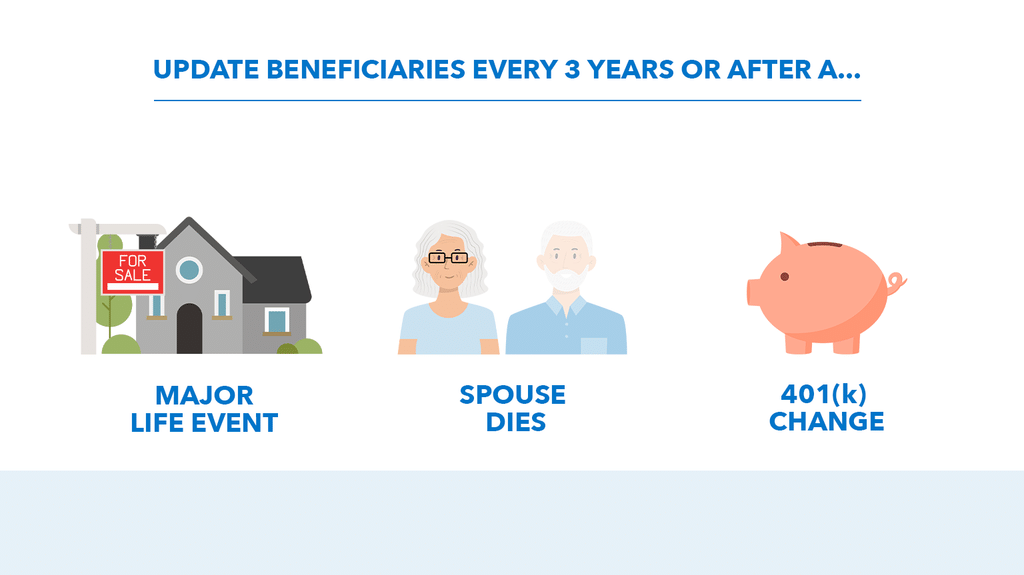
Loren recommends revisiting them periodically and after major life changes. “You want to check them at least every three years or upon major life events.”
Consider reviewing the beneficiary designation currently on file for each IRA, 401(k), life insurance policy, and annuity to see whether it still reflects your wishes.
Mistake #3: Setting up joint tenancy thinking it protects the family
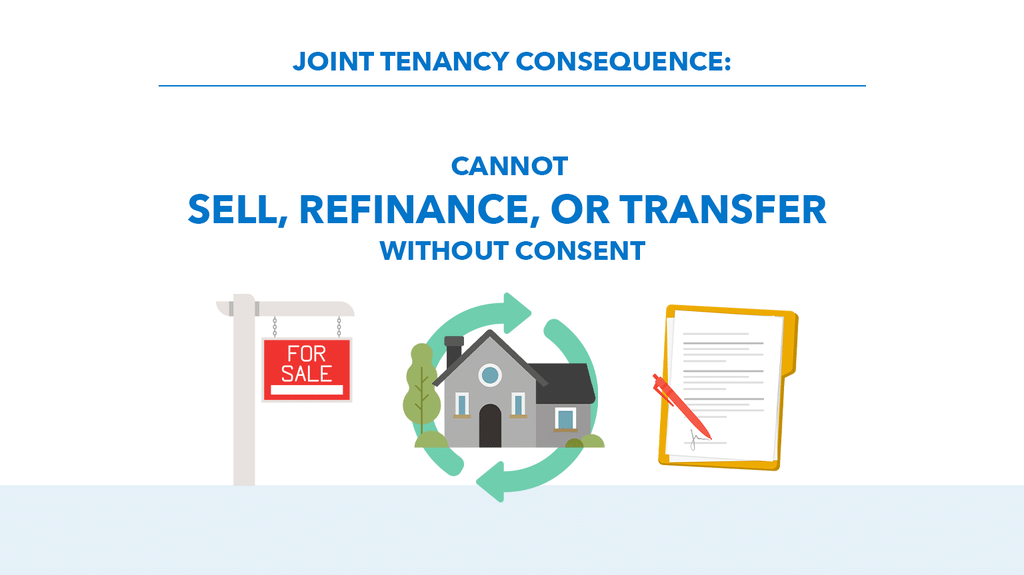
Joint tenancy with rights of survivorship can make transferring an asset simple. When one joint owner dies, the surviving owner generally receives the deceased owner’s share.
That simplicity can make joint ownership attractive. But adding another person as an owner also gives that person control over the asset while you are alive.
Take a checking account as an example. A parent may add an adult child to the account so the child can help manage finances later in life. But once that child is a joint owner, the child has ownership rights too.
Chawn explains, “So it’s important to understand what that joint tenant ownership really means and what control you are providing to someone else.”
Returning to our earlier hypothetical, suppose Charlie is a 50% joint owner of an account holding $200,000. Legally, Charlie owns $100,000. If Charlie goes through a divorce, faces a lawsuit, or has creditor issues, his ownership interest could create complications involving the account.
There may be another way to accomplish the intended goal without making Charlie an owner. For example, a bank account may allow the owner to add a payable-on-death beneficiary. Charlie would not own the money during the parent’s lifetime, but the account could pass to him after the parent’s death.
The larger lesson is to understand what ownership means before adding another person’s name to an asset.
Mistake #4: Leaving a large pre-tax IRA to heirs without a tax strategy
Leaving retirement savings to the next generation may be part of your legacy plan. But the type of account you leave can make a significant difference.
For many non-spouse beneficiaries, an inherited IRA generally must be depleted within a 10-year period. That can create a challenge when the person inheriting the money is already in a high-earning stage of life.
Consider this hypothetical example: a $500,000 IRA is inherited by one child. Ignoring investment growth for simplicity, spreading $500,000 across 10 years would represent an additional $50,000 per year.
Now suppose the child is single and earns $180,000 annually. Adding inherited IRA distributions to his existing income could push some of his taxable income into a higher federal tax bracket, using 2026 single filer tax brackets.
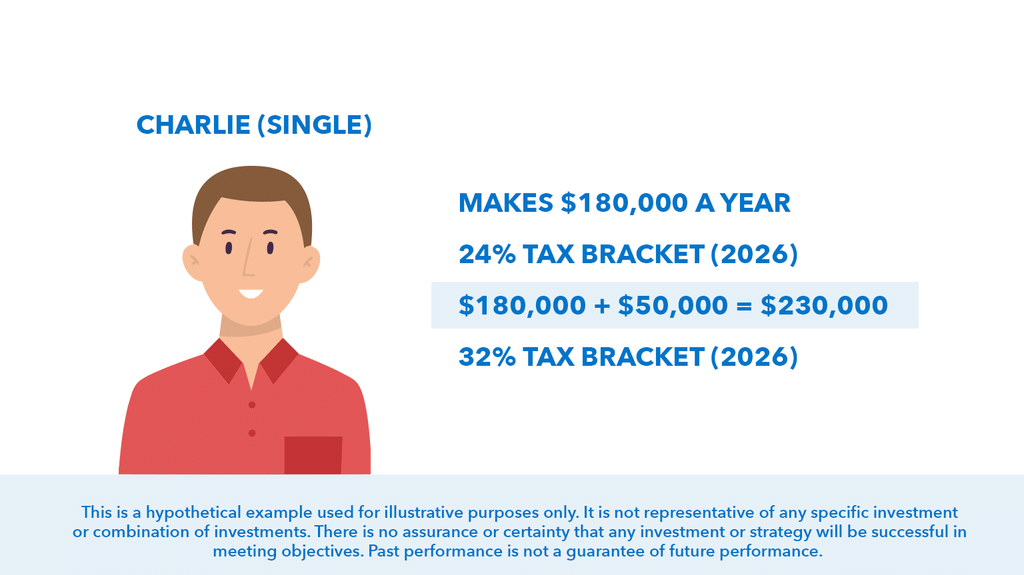
As Chawn explains, “The problem that this can lead to is your child might be at their highest earning part of their career, so they’re already filling up their tax brackets to a certain level.”
That is why legacy planning and tax planning often need to work together.
In these hypothetical examples, the parents may have had opportunities during their lifetimes to convert some pre-tax retirement assets to a Roth IRA and pay taxes at their own tax rate. The goal is not simply to ask how much money will be left behind, but also what type of account the beneficiary will inherit and what the potential tax consequences may be.
Review the Full Picture Before Making a Change
The common thread running through these mistakes is that a decision involving one asset can affect several other areas of a financial plan.
Before changing a deed, adding a joint owner, updating an estate plan, or deciding how to pass along a retirement account, consider what happens under different circumstances.
What happens if the joint owner gets divorced? What happens if there is a lawsuit? Who controls the asset while you are alive? What happens from a tax standpoint when you die? Does the beneficiary designation on the account match what your estate documents say you want?
State laws matter, too. Estate and property laws vary, which makes it important to understand the rules that apply where you live and involve the appropriate legal and tax professionals when making estate planning decisions.
Estate planning is about more than getting documents signed and putting them away. Your assets, family, and circumstances can change over time. Periodically reviewing how assets are titled, who is listed as a beneficiary, and how each part of the plan is designed to transfer can help you better understand whether your estate plan still reflects your intentions.
Watch the full episode on YouTube and learn more about taking steps to help make sure your assets ultimately go where you intend.
—
This is a hypothetical example used for illustrative purposes only. It is not representative of any specific investment or combination of investments. There is no assurance or certainty that any investment or strategy will be successful in meeting objectives.