Debunking Social Security Myths: A Guide To Navigating Your Benefit

Understanding Social Security is important as it plays a significant role in retirement planning. We help you make sense of the facts and provide insights into optimizing Social Security benefits to help you navigate this important income decision. 

–––––––––––––––––––––––––––––––––––––––––––––––––––––––––––––––––––––––––––––––––––––––––––––

Why social security decisions matter

The conversation began with Retirement Planners Loren Merkle and Chawn Honkomp emphasizing the importance of making informed Social Security decisions. Chawn noted, “It’s a huge decision with a lot of complexity and confusion” – a sentiment many pre-retirees can relate to. With more than 81 Social Security options available for married couples, this crucial decision shapes your financial security during retirement.  
Fact or fiction: Addressing Common myths

In the episode, Loren and Chawn engaged in a game of “Social Security Fact or Fiction,” tackling several statements about Social Security. 

Fact or fiction: social security will run out of money before i retire

Both Loren and Chawn identified this as fiction, acknowledging the widespread concern but emphasizing the current legislative options available to sustain Social Security. Loren explained that while the federal government has to make some tough choices, there are various mechanisms they could employ, such as adjusting the taxable income cap or increasing the full retirement age. This ensures a level of continuity for those already benefiting from Social Security or approaching eligibility. 

fact or fiction: a surviving spouse, at full retirement age or older, generally gets 100% of the worker’s basic benefit amount

This one was deemed generally true but with nuances. Loren highlighted this benefit as one of the least understood aspects, bringing to light its complexity based on multiple factors like age, eligibility, and marital status. A surviving spouse does typically receive the higher of the two benefits if both were already claiming, but the specifics can vary significantly. 

fact or fiction: an ex-spouse’s benefit comes out of your own benefit

Both planners quickly labeled this as fiction, clarifying that an ex-spouse drawing a benefit based on your income doesn’t reduce your benefits at all. Loren reassured viewers that such claims are entirely separate, with no impact on either party’s benefits. 

fact or fiction: The annual COLA increase is guaranteed

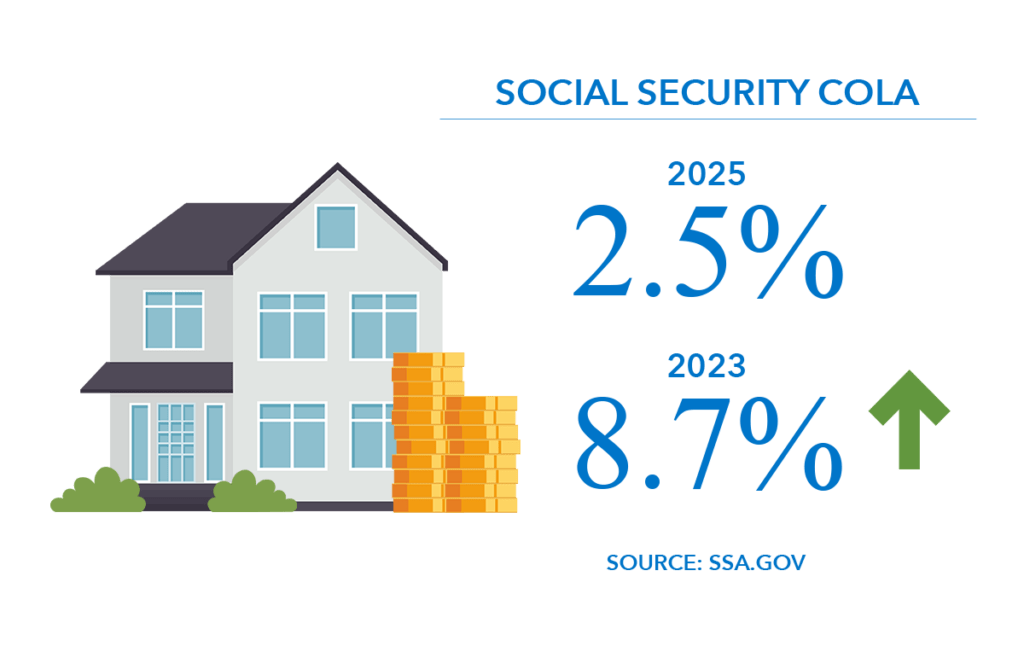
For 2025, the Cost of Living Adjustment (COLA) is 2.5%, contrasting with 8.7% in 2023. Loren pointed out that COLAs help counterbalance inflation but aren’t guaranteed. Periods with 0% COLA increase, like 2010, 2011, and 2016, serve as a reminder of this variability. 
Earnings test

Fact or fiction: i won’t pay taxes on my social security benefits

Social Security benefits might be taxable depending on your other income sources and filing status. Loren and Chawn explained that a well-crafted tax strategy could minimize or even eliminate these taxes. In 2025, for married couples filing jointly, up to 85% of their benefits could be taxable if their combined income is above $44,000. For single filers, up to 85% of their Social Security benefit could be taxable if their provisional income is above $34,000. Early planning is essential to navigate these thresholds efficiently. 

Conclusion

This episode of “Retiring Today with Loren Merkle” provided important insights into Social Security’s complexities. Understanding these nuances can help you maximize this retirement benefit. 

Click here to watch the full episode “Debunking Social Security Myths” on YouTube!

Source: SSA.gov
FOLLOW US ON SOCIAL

Visual-Insights-Newsletter-Ad_v2

Sign-up for our Visual Insights Newsletter for the latest retirement information and strategies – straight to your inbox.

  • This field is for validation purposes and should be left unchanged.

Discover more strategies you could be missing out on
man standing next to a few words of text and retirement related iconography.

5 Reasons People Put Off Retirement Planning and What the Delay Could Cost

Retirement planning is easy to push down the to-do list, especially when retirement still feels years away. But waiting can mean missed opportunities involving taxes, investments, health care, and retirement income. Here are five common reasons people put off creating a written retirement plan and why starting earlier can make a difference.  1. Conflicting Priorities Make Planning…

Read More...
woman looking neutral next to a heading of text and a cartoon visual representing long-term care.

A New Way to Think About Paying for Long-Term Care 

Long-term care can become one of the largest expenses in retirement. Understanding what qualifies as long-term care, what care can cost, the limitations of traditional long-term care insurance, and newer approaches to preparing for the expense can help you build it into your overall retirement plan. What Does Long-Term Care Really Mean?  Long-term care can be difficult…

Read More...
Man looking unsure next to a few lines of text. A couple talking at a table is faded into the background.

The 5 Retirement Conversations Every Couple Should Have 

Retirement brings decisions that affect both spouses, from how you want to spend your time to what happens to income when one spouse dies. These five conversations can help couples identify differences, understand potential financial consequences, and build a retirement plan around the life they want to share. — Retirement planning involves plenty of numbers, but some of the most important…

Read More...
man and woman pointing up at a headline with YouTube button overlaid.

Retirement Planner vs. Financial Advisor: What’s the Difference?

As retirement gets closer, the financial guidance you need may change. Understanding the difference between investment-focused advice and comprehensive retirement planning can help you identify whether your current approach addresses income, taxes, Social Security, health care, investments, lifestyle, and legacy. — For decades, much of your financial life may have centered on one goal: saving and investing for the…

Read More...
man standing next to buckets with a puzzled look on his face.

Will Your Money Last as Long as You Do?

Saving enough for retirement is only part of the equation. Learn how identifying your income gap, planning for inflation and taxes, and dividing savings into now, later, and forever buckets can help turn a retirement nest egg into an income strategy designed to last.  Saving $1 Million Is Different From Having a Plan Reaching a retirement savings goal can feel like…

Read More...
man standing in front of two market charts looking serious.

6 Money Moves for Market Swings

Market volatility is inevitable, but it does not have to derail your retirement plans. These six retirement planning moves can help you prepare for market swings, protect your retirement income, manage investment risk, uncover potential tax opportunities, and take advantage of market downturns.  — Market swings can feel very different when retirement is getting closer.  While you are working…

Read More...

Ready to take your retirement to the next level?

Let's chat! Schedule a RetireReady Call to talk with a retirement planner about your retirement vision.

Ready to take your retirement to the next level?

Let's chat! Schedule a RetireReady Call to talk with a retirement planner about your retirement vision.

Call Now Button