Retirement brings decisions that affect both spouses, from how you want to spend your time to what happens to income when one spouse dies. These five conversations can help couples identify differences, understand potential financial consequences, and build a retirement plan around the life they want to share.
—
Retirement planning involves plenty of numbers, but some of the most important work may begin with a conversation between spouses.
When do you each want to retire? How much will your desired lifestyle cost? What happens to your income when one of you dies? How will you pay for health care? And do you have a written plan that brings all of those decisions together?
Couples do not always have the same answers. Talking through those differences before retirement can make it easier to put numbers around your goals and understand the trade-offs involved.
1. What Does Retirement Actually Look Like for Both of You?
It is easy to talk generally about retirement when it is years away. You might picture traveling, golfing, spending time with grandchildren, or finally having more time for hobbies.
As retirement gets closer, those ideas need more detail.
Loren Merkle, CFP®, RICP®, Certified Financial Fiduciary®, says, “The more detail that you have around what’s going to make you happy in this next phase of your life, the more that you can put planning around that.”
That detail matters because two spouses can have very different ideas about retirement without realizing it.
One may want to travel extensively while the other wants to stay close to grandchildren. One may want to retire at 62 while the other wants to work until 68. One may picture buying a second home while the other would rather downsize.
Even a difference in expected monthly spending can significantly change the retirement plan.
Consider the hypothetical example of John and Sue. They initially believe they will need $6,000 a month to support their retirement lifestyle. John wants to fish and attend his grandchildren’s soccer games. Sue wants to do those things, too, but she also wants to travel and continue quilting.
Once those additional expenses are considered, their lifestyle might actually require $9,000 a month rather than $6,000.
That $3,000 monthly difference can have long-term implications for how much they need to save and how their retirement income is structured.
Spouses may also disagree about helping adult children financially, purchasing a vacation property, or spending significant money on a hobby. Putting numbers around those choices can help move the discussion from an emotional decision to a planning decision.
Chawn Honkomp, CFP®, RICP®, CPA, Certified Financial Fiduciary®, offers another way to frame lifestyle spending: “Do you want to own or rent your fun?”
For some couples, that could mean buying a second home or recreational vehicle. For others, renting allows them to visit different places without committing a large portion of their retirement savings to one purchase.
There is not necessarily one correct retirement vision. The important part is understanding what each spouse wants and what it will take financially to make those goals possible.
2. What Happens to Our Income if One of Us Dies?
It may be one of the most difficult retirement conversations, but couples should understand what happens financially when one spouse dies.
Income can change substantially.
For couples with pensions, the decision begins with the pension election. Depending on the pension, retirees may have choices that provide income for one life or provide some level of survivor benefit.
“If you have a pension, you have many different pension election options,” Loren explains. “Are you going to take that pension income based on just your life? If so, when you pass away, your spouse is not going to receive any of that income, so how is your spouse going to continue to live or how is your spouse going to replace the income from that pension?”
Social Security also changes after the death of a spouse.
Chawn explains, “Generally speaking, let’s assume both benefits are turned on. People are several years into their retirement. Someone passes away, the lower benefit will go away, and the larger benefit will remain.”
That means couples should consider Social Security decisions not only in terms of the income they will receive while both spouses are living, but also what those decisions could mean for the surviving spouse.
Taxes can change, too.
Consider another hypothetical example using John and Sue. Suppose they have $100,000 of taxable income while married. If John dies and Sue’s spending needs decline by only 30%, she may still need approximately $70,000 annually.
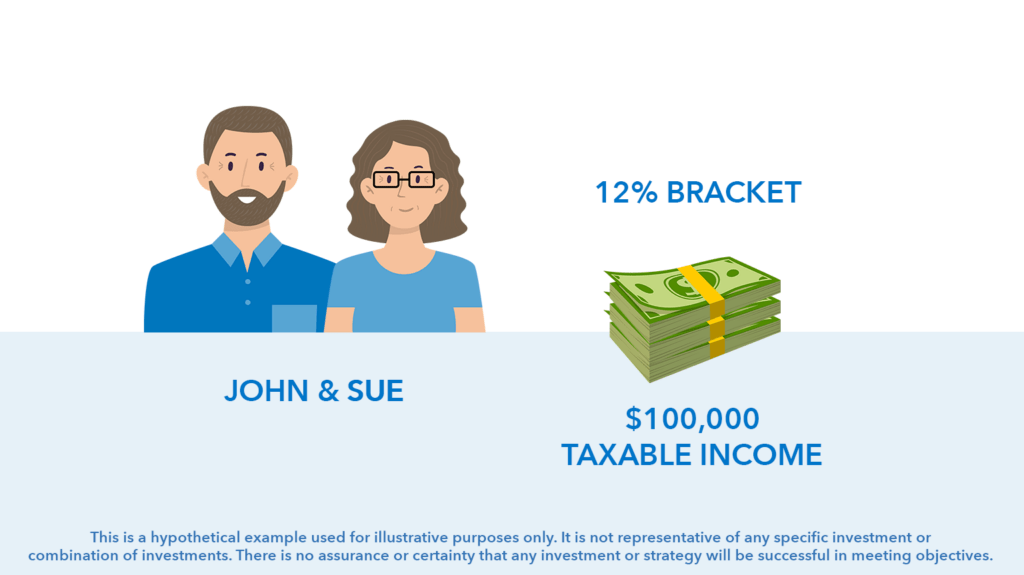
Some income may disappear, but many expenses remain. Housing, utilities, property taxes, insurance, and health care do not necessarily fall by half simply because the household has one person instead of two.
At the same time, Sue would eventually be filing taxes as an individual rather than married filing jointly. That combination can potentially expose more of her income to higher tax brackets.
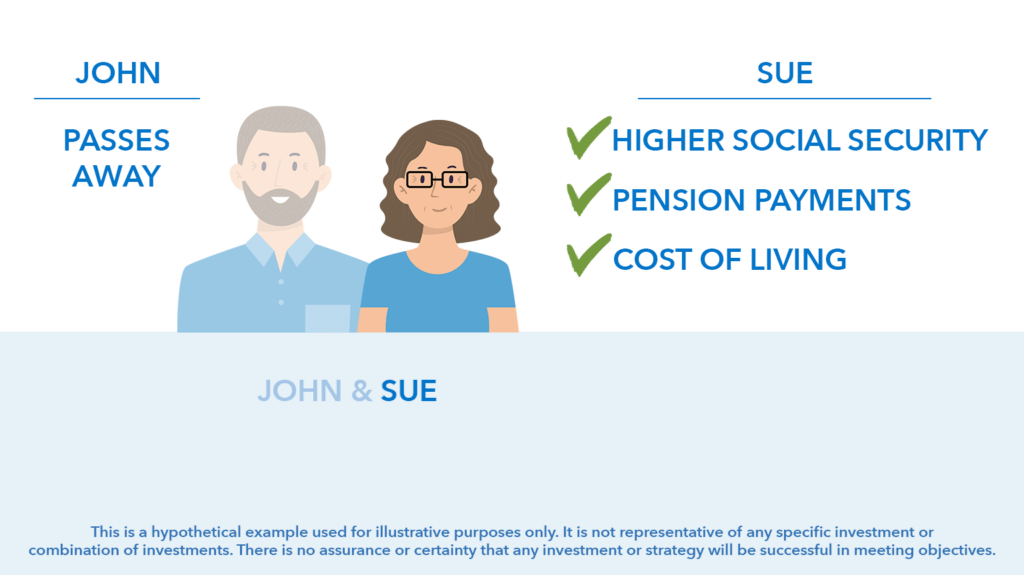
Planning for the surviving spouse means looking beyond how much money is available today and considering how income, taxes, and expenses could change later.
3. Are We Paying More in Taxes Than We Have To?
Many people assume their tax bill will automatically fall once they retire.
It might. But a lower tax bill immediately after retirement is not necessarily the end goal.
“For many people, with their tax planning strategies, one of the best opportunities to start meaningful tax planning is that first full calendar year when you’re both retired or maybe when just one of you retires,” Loren says.
Retirement can create years in which taxable income is temporarily lower, potentially creating opportunities to evaluate strategies such as Roth conversions or tax-loss harvesting.
This can be particularly important for couples who accumulated much of their retirement savings in traditional 401(k)s and IRAs.
Those accounts generally contain pre-tax dollars. Withdrawals are generally taxable as ordinary income, and eventually required minimum distributions may force money out of those accounts whether the retiree needs the income or not.
“At 73 for a lot of people, it’s moving out to 75 for some of you,” Chawn says. “That’s going to be a stage in your retirement journey where now, you might get forced up into even a, even a higher tax bracket.”
Rather than looking only at this year’s tax bill, retirement tax planning involves considering taxes over many years.
That can include discussing how much of your savings is taxable, when you expect to begin Social Security, when required minimum distributions begin, and whether there are years when intentionally recognizing additional taxable income may be worth evaluating as part of a long-term tax-planning strategy.
4. Do We Have a Plan to Pay for Health Care?
Health care deserves its own retirement conversation because costs can be substantial and needs are difficult to predict.
“As I think about all the risk categories that are part of someone’s retirement journey, this might be the one that we have the least control over,” Chawn says.
Couples retiring before Medicare eligibility at age 65 need to determine how they will obtain coverage during the gap between retirement and Medicare.
After 65, the decisions continue. Retirees need to evaluate Medicare coverage options, premiums, and out-of-pocket expenses.
Long-term care introduces another layer of uncertainty.
According to Fidelity, a 65-year-old couple retiring in 2026 could spend more than $300,000 on health care and medical expenses during retirement.
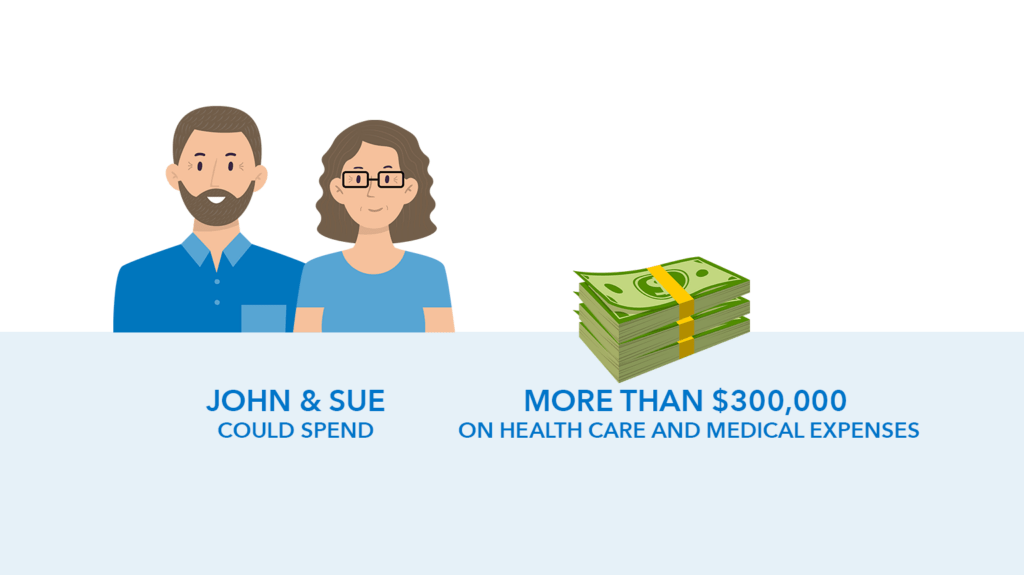
Those figures reinforce why health care should be incorporated into the retirement budget rather than treated as an expense to address later.
5. Do We Have a Written Retirement Plan That Covers All Six Areas?
After couples talk through what they want retirement to look like, along with income, taxes and health care, the next question is how those pieces fit together.
A retirement plan involves more than an investment portfolio.
At Merkle Retirement Planning, the written retirement plan is called the RetireSecure Roadmap and includes six pillars: lifestyle, income, taxes, investments, health care, and legacy.
“The first pillar is your lifestyle,” Loren says. “What do you want your retirement to look like? This is really the manifestation of what your retirement dreams are.”
The other five pillars help support that lifestyle.
A decision involving one pillar can also affect several others. When you begin Social Security, it affects income and potentially taxes. A Roth conversion can affect taxes and investments. Retiring before 65 creates health care considerations that can affect the amount of income needed.
“All six of those are very much combined together,” Loren says.
That interconnectedness is one reason a written plan can be valuable. Instead of making each retirement decision independently, couples can evaluate how one choice could affect other parts of their financial lives.
Chawn explains, “When life happens, we already have this plan. We can slow down a little bit when events happen. Now we can just kind of read and react and make new decisions that fit within that overall plan.”
Start the Conversation Before You Need the Answer
Retirement conversations do not have to begin with spreadsheets and account statements.
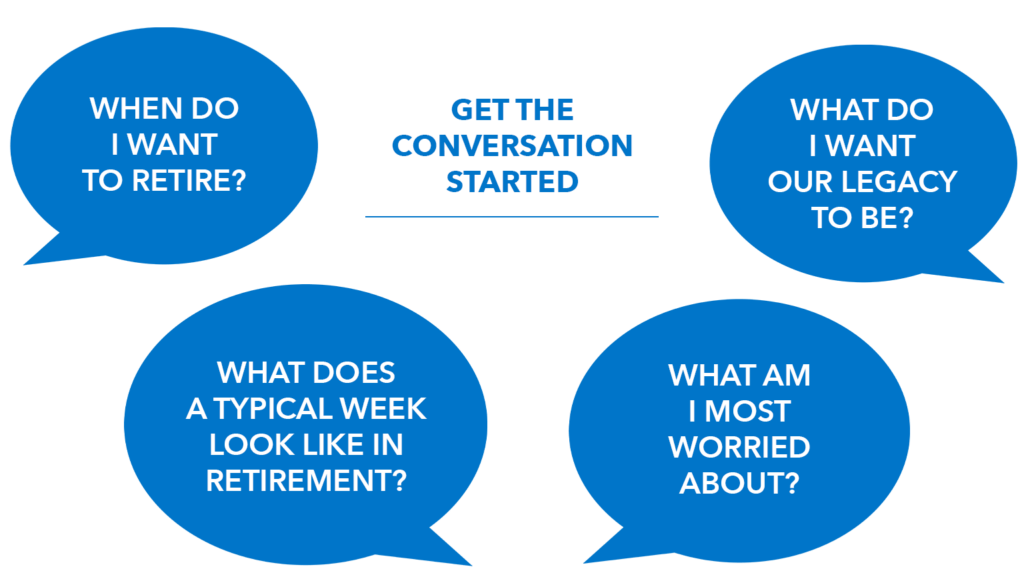
Couples can start by separately answering a few basic questions: When do I want to retire? What does a typical day in retirement look like? What am I most worried about? What do I want my legacy to be?
Comparing those answers may uncover areas where you are already aligned and others you have never discussed.
And those conversations should not end once retirement begins. Goals, hobbies, health, family circumstances, and financial priorities can all change over a retirement that may last 20 or 30 years.
As Chawn says, “Having that conversation once is not enough, especially when it comes to a retirement journey, and we’re talking about the rest of somebody’s lives.”
The goal is not for spouses to agree on every detail from the beginning. It is to understand what each person wants, identify the financial decisions those goals create, and build a plan designed to remain flexible enough to change along with you.
—
Watch the full episode on YouTube and learn more about how discussing retirement with your spouse may bring clarity to your retirement plan.
Source: (2026) Fidelity Investments® Shares 25th Annual Retiree Health Care Cost Estimate, Highlighting the Importance of Incorporating Potential Health Expenses in Retirement Planning, Fidelity https://newsroom.fidelity.com/pressreleases/fidelity-investments–shares-25th-annual-retiree-health-care-cost-estimate–highlighting-the-importa/s/0dd560b4-98cb-492e-bdec-f7168f97aede
—