Retirement can give you thousands of hours of your time back each year, but deciding how you want to spend that time is an important part of retirement planning. From health and relationships to purpose and adventure, here are six areas to consider as you design your retirement and several year-end tax strategies that may help you make the most of the money you saved.
What Will You Do With 2,000 Extra Hours a Year?
Retirement planning often begins with financial questions. Do you have enough saved? When should you claim Social Security? How will you create income without a paycheck?
But there is another question that can be just as important: What are you actually going to do when you retire?
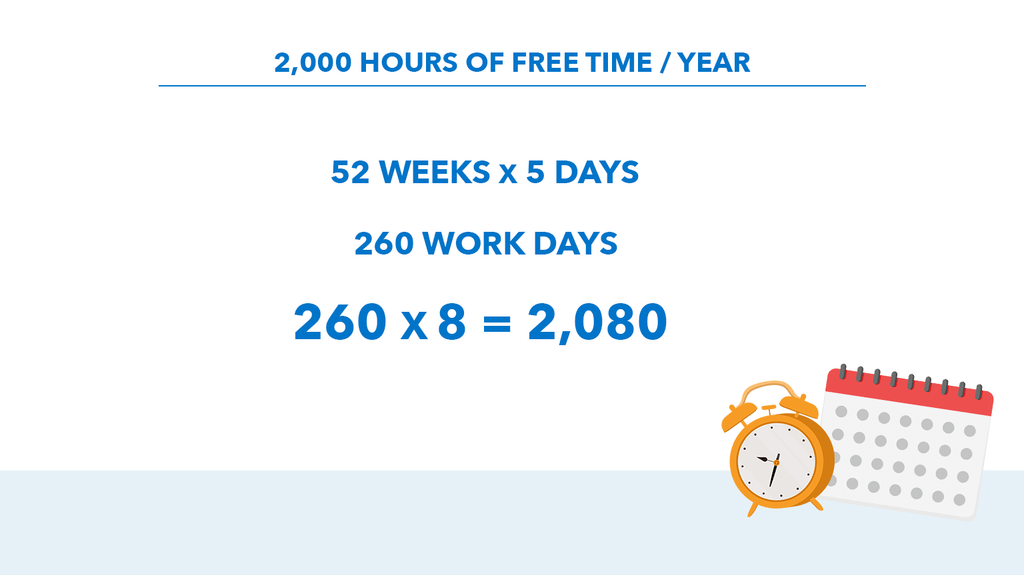
A traditional 40-hour workweek adds up to about 2,080 hours a year. Retirement potentially gives you much of that time back, and that does not include commuting or the additional hours many people spend thinking about work when they are technically off the clock.
For someone who has spent 30 or 40 years building a career, that can be a major adjustment.
Loren Merkle, CFP®, RICP®, Certified Financial Fiduciary®, says people who spend time thinking about that transition may have an easier time adjusting. “Those who really put some time and effort into what that lifestyle in retirement’s going to look like and what your identity is going to look like do make that transition a little bit easier.”
That lifestyle discussion can also affect the decision of when to retire. Some people may be financially prepared but continue working because they have not figured out what comes next.
Start With the Retirement You Want
Before deciding how much retirement will cost, it helps to have a clearer picture of the life you want those savings to support.
That means going beyond a general goal of “travel more” or “spend time with the grandkids.” Think about an ordinary Tuesday in retirement. What time do you get up? Who do you spend time with? Are you traveling frequently or mostly staying close to home? What hobbies would you like to try? What would make you feel like your days have purpose?
Chawn Honkomp, CFP®, RICP®, Certified Financial Fiduciary®, ChFC®, CPA, says those conversations can help people begin putting a picture around retirement. “It helps people start, you know, being able to paint that picture of what they want their retirement to be.”
For couples, those discussions can be especially revealing. One spouse may picture retirement filled with travel while the other wants to stay close to grandchildren. Talking through those differences before retirement gives both people an opportunity to build a shared vision rather than discovering the differences after the paychecks stop.
Six Areas That Can Shape a Fulfilling Retirement
There is no single formula for a happy retirement. What matters most will vary from person to person, and priorities may change as you move through retirement. But six areas can provide a starting point for thinking beyond the numbers.
Health: Your retirement savings can provide opportunities, but your health can influence your ability to enjoy them. Staying active and prioritizing your physical well-being can become increasingly important as retirement progresses.
Purpose: Leaving a career can also mean leaving behind responsibilities, accomplishments, and a professional identity that provided purpose for decades. Retirement creates an opportunity to redefine that purpose.
Loren cautions that you may not figure it out immediately. “Give yourself time, give yourself time to breathe, relax, and kind of settle into what this new life looks like.”
Relationships: Work naturally puts you around other people. In retirement, maintaining friendships and building new relationships can require more intentional effort. Social circles may also change as people move, friendships evolve, or loved ones pass away.
Finances: Money may not be the only ingredient in a fulfilling retirement, but having a financial plan may help you feel more prepared to focus on everything else. The goal is to understand how your income, savings, and spending work together to support the lifestyle you envision.
Giving: Retirement may give you more opportunities to give your time, money, or experience to others. That could mean volunteering, serving on a board, supporting an organization you care about, or simply having more time to help family and friends.
As Loren explains, “Whatever you’re giving of yourself, that can be extremely rewarding and help boost your confidence and help boost your purpose as far as what you’re going to do going forward.”
Adventure: Retirement can also be an opportunity to try something new. Travel, hobbies, new experiences, and even a little trial and error can help fill those 2,000-plus hours with things you may not have had time to pursue while working.
Turn the Lifestyle Plan Into a Financial Plan
Once you have a better idea of what you want retirement to look like, the financial questions become more specific.
Instead of simply asking, “Do I have enough?” you can begin asking, “Do I have enough to support this retirement?”
If travel is important, it can become part of the spending plan. If you want to retire early, you can consider how you will cover health care before Medicare. If giving is a priority, charitable strategies can be incorporated into the plan.
Taxes are another important piece. The amount you ultimately have available to spend is affected not only by what you saved, but also by how and when those dollars are taxed.
Some year-end tax-planning strategies generally must be completed by December 31st.
Consider Your Roth Conversion Window
A Roth conversion involves moving money from a pre-tax retirement account into a Roth IRA. Generally, the taxable portion of the conversion is included in your income in the year of the conversion. Qualified Roth IRA distributions can later be excluded from income.
The timing can matter.
Chawn points to the years before other sources of retirement income begin as potential planning opportunities. He says developing a long-term tax plan earlier can provide more time to evaluate whether Roth conversions or other strategies may be appropriate.
Look for Tax-Loss Harvesting Opportunities
Year-end can also be a time to review taxable investment accounts for potential tax-loss harvesting opportunities.
The basic idea is to intentionally realize certain investment losses that may be used to offset capital gains. However, investors need to be aware of the wash-sale rule. Generally, a loss may be disallowed if you purchase substantially identical securities within 30 days before or after selling the investment at a loss.
As Loren says, “We need to look at that as a possible strategy if that’s applicable to you.”
Don’t Overlook Required Minimum Distributions
Required minimum distributions, or RMDs, can also become an important year-end consideration.
Generally, traditional IRA owners must begin RMDs at age 73. The first RMD can be delayed until April 1st of the following year, but doing so generally means taking both the first and second RMD during that same calendar year. Subsequent RMDs are generally due by December 31st each year.
That first-year decision deserves attention because taking two RMDs in one tax year could result in more taxable income during that year.
As Chawn explains, “That could be an effective strategy for some, but it could be a disaster for others.”
If You Give to Charity, Consider a QCD
For people who are charitably inclined, a qualified charitable distribution, or QCD, may provide another way to coordinate generosity with a retirement tax strategy.
IRA owners age 70½ or older may generally make a QCD directly from an eligible IRA to a qualified charity. A QCD can also count toward all or part of an RMD, when applicable.
The strategy can be particularly relevant for someone who already plans to give to a church, school, or charitable organization.
Chawn describes it this way: “If you’re going to donate, it’s a more efficient way to do that same donation.”
Plan for More Than the Retirement Date
Retirement planning is not just about reaching the day when you can stop working. It is about preparing for what comes afterward.
Think about the 2,000-plus hours you may get back each year. Consider your health, purpose, relationships, finances, giving, and adventures. Talk through the vision with your spouse or the people who matter most to you.
Then look at the financial and tax decisions that may help support that vision.
A retirement plan can do more than answer whether you have enough money to retire. It can help connect the money you spent decades saving to the life you spent decades looking forward to.
Watch the full episode on YouTube and learn more about year-end tax strategies that may help you make the most of the money you saved.