Long-term care can become one of the largest expenses in retirement. Understanding what qualifies as long-term care, what care can cost, the limitations of traditional long-term care insurance, and newer approaches to preparing for the expense can help you build it into your overall retirement plan.
What Does Long-Term Care Really Mean?
Long-term care can be difficult to think about because there are so many unknowns. Will you need it? What kind of care might you need? How long could you need it? And perhaps most importantly, how would you pay for it?
Long-term care is generally triggered when someone loses the ability to perform two of six activities of daily living: eating, bathing, transferring, continence, toileting, and dressing. Memory care may also qualify.
That does not necessarily mean moving into a nursing home. Care can take many forms, including home health care, adult day care, facility care, and informal care.
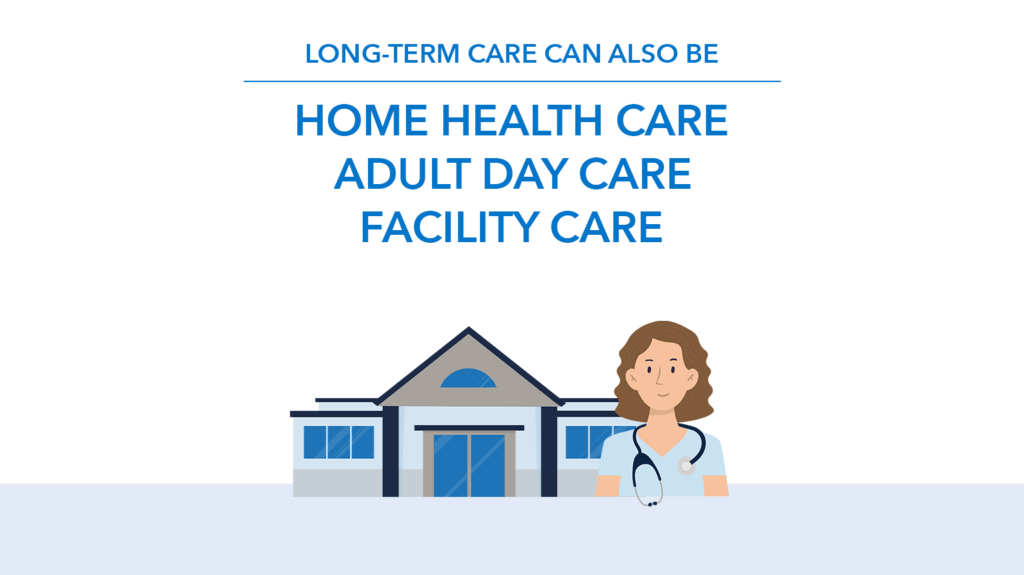
As Loren Merkle, CFP®, RICP®, Certified Financial Fiduciary®, explains, “It’s worth noting that it’s not just a nursing home.”
Receiving care at home has become increasingly common, but regardless of where care takes place, the potential need deserves consideration as part of a retirement plan.
The Odds of Needing Care Are Significant
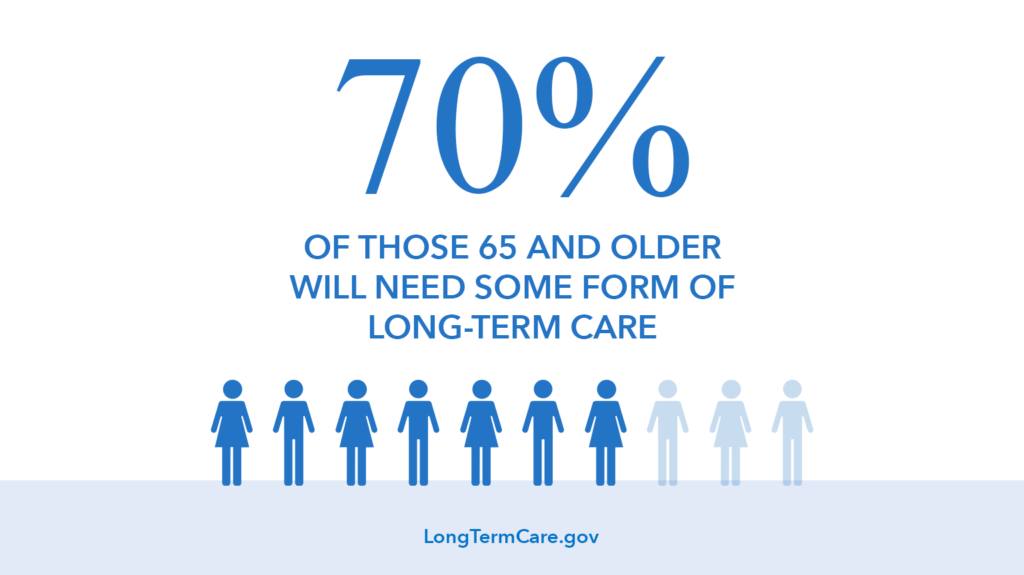
For people 65 and older, there is a 70% chance of needing some form of long-term care. Women need care for an average of 3.7 years, while men need it for an average of 2.2 years, according to LongTermCare.gov.
Memory care can extend much longer. The average length of long-term care following an Alzheimer’s diagnosis is eight years.
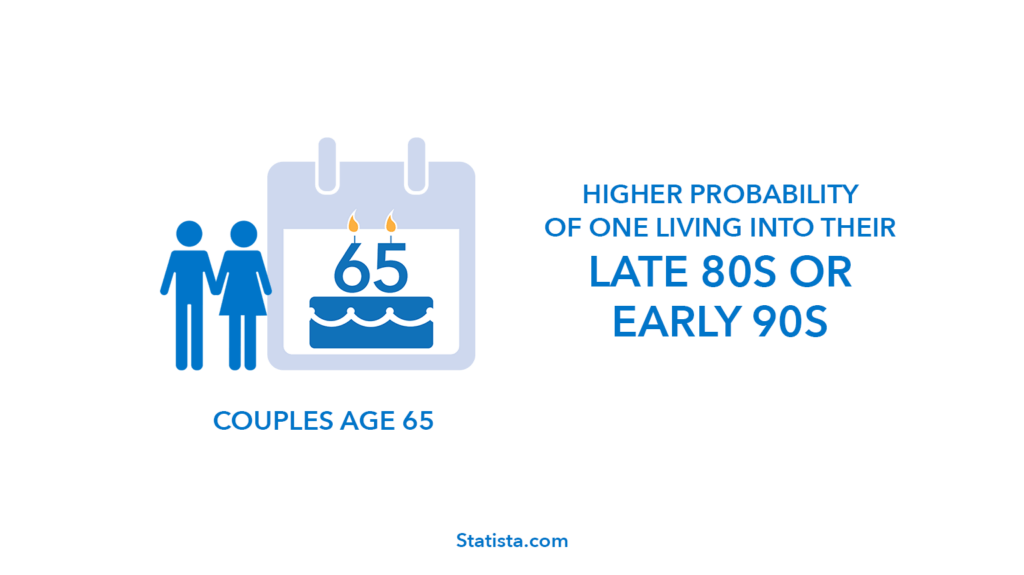
Longer life expectancies add another dimension. For a married couple at age 65, there is at least a 50% chance one spouse will live past age 90.
“What that means is that you have to plan for later in life from a financial standpoint, whether you’re still healthy and you want to continue to live the lifestyle that you’ve grown accustomed to, or you need some kind of additional care,” Loren says.
The potential duration of care matters because the costs can add up quickly.
How Much Can Long-Term Care Cost?
These are the national median costs of long-term care according to the 2025 CareScout Cost of Care Survey:
- Assisted living community: $74,400 a year
- Nursing home, semi-private room: approximately $114,000 a year
- Nursing home, private room: approximately $129,000 a year
- Skilled nursing care at home: approximately $90 an hour
Those expenses can affect more than a retiree’s monthly budget. They can potentially reduce assets accumulated over decades and change what remains for a surviving spouse, children, or grandchildren.
Medicare Is Not a Long-Term Care Plan
Another misconception is that Medicare will take care of long-term care expenses.
AnnaMarie Morrow, Director of Medicare & Long-Term Care, explains that Medicare coverage for skilled nursing is limited. “Medicare stops paying (after) 100 days, that’s slightly over three months, and that’s hard to wrap your head around.”
Compare that coverage period with an average need according to LongTermCare.gov of 3.7 years for women or 2.2 years for men, and the gap becomes clear.
That makes it important to think beyond Medicare when considering how an extended care need could affect a retirement plan.
The Challenges With Traditional Long-Term Care Insurance
Traditional long-term care insurance has historically been one way to address this risk. Some older policies continue to provide valuable coverage, but the market has changed.
Premium increases can make existing policies increasingly expensive. Loren describes the dilemma some policyholders now face: “Do you want to let those premiums go that you’ve invested into this long-term care insurance policy, or do you want to pay 40, 50, 60% more on an ongoing basis with no guarantee that it’s not going to continue to rise after that three-year timeframe?”
Traditional policies can also require extensive health underwriting. By the time someone becomes concerned about long-term care, health conditions may make obtaining coverage difficult.
There is another drawback: if the policyholder never needs long-term care, premiums paid into a traditional policy may not provide a benefit to heirs.
These considerations have led some retirees to self-insure, while others are exploring different insurance-based approaches.
A Modern Hybrid Approach
One option to consider combines long-term care coverage with a potential benefit for beneficiaries. It is sometimes called a hybrid approach.
To demonstrate how it can work, AnnaMarie uses the hypothetical example of a woman named Sue.
The approach is guaranteed issue, meaning there are no health questions required to obtain the base coverage. Sue can also choose to participate in a roughly 30-minute video interview involving cognitive and physical tasks. Based on the results, she may qualify for a multiplier of one, two, or three times the amount committed to the strategy.
In the hypothetical example, Sue qualifies for the three-times multiplier.
Her retirement plan identifies $250,000 from what the planners describe as her “forever bucket” of money. She uses that amount for a one-time premium.
With the three-times multiplier:
$250,000 × 3 = $750,000 available for long-term care benefits, subject to the policy’s terms and eligibility requirements.
If Sue later qualifies for long-term care, the $750,000 benefit is designed to be distributed over five years, or 60 months.
That works out to:
$750,000 ÷ 60 months = $12,500 per month.
As AnnaMarie explains, “Sue will receive $12,500 a month tax-free for long-term care should she need it.”
What Happens If Care Is Never Needed?
The hybrid approach also addresses one of the concerns people may have with traditional long-term care insurance: paying for coverage they never use.
In Sue’s hypothetical example, her original $250,000 is tied to an account that can receive a portion of positive S&P 500 performance up to certain limits.
If Sue never needs long-term care, her original $250,000, plus applicable growth, can pass to her beneficiaries.
That creates two potential purposes for the money: helping fund long-term care if it is needed or becoming part of a legacy if it is not.
Start With the Retirement Plan, Not the Product
The hypothetical example is not simply about deciding to put $250,000 into a particular strategy. The amount was identified only after looking at Sue’s entire retirement picture.
Loren explains, “That’s really where we start is we build out a plan for Sue and say, ‘If you need long-term care and you choose to self-insure,’ meaning you don’t have long-term care insurance, ‘here’s what your long-term care risk is. Here’s how it impacts your, your plan long term.’”
From there, different scenarios can be compared. That might mean self-insuring, considering traditional coverage or evaluating a hybrid approach. Even within the hybrid example, the plan can show what happens if the individual receives a one, two, or three-times multiplier.
The goal is to understand how each choice could affect the broader retirement plan before making a decision.
Avoiding the Conversation Is Still a Decision
Long-term care planning can be uncomfortable because it requires thinking about circumstances no one hopes to experience. But the potential costs, increasing longevity, and limitations of Medicare make it difficult to ignore.
As AnnaMarie puts it, “Avoiding it is a decision too.”
Planning does not mean assuming you will spend years in a nursing home or memory care facility. It means considering the possibility, understanding what the financial impact could be, and deciding how you would prefer to handle that risk.
Whether the answer is self-insuring, an existing traditional policy, a hybrid strategy, or another approach, long-term care is one more piece that can be considered alongside income, investments, taxes, health care, and legacy when building a retirement plan.
—
Watch the full episode on YouTube and learn more about long-term care and how it could impact your retirement.
Sources:
May 2024. When to Start Receiving Retirement Benefits Social Security Administration https://www.ssa.gov/pubs/EN-05-10147.pdf
March 2, 2026. CareScout Releases 2025 Cost of Care Survey Results Genworth https://investor.genworth.com/news-events/press-releases/detail/1054/carescout-releases-2025-cost-of-care-survey-results
March 18, 2020 How Much Care Will You Need? LongTermCare.gov https://acl.gov/ltc/basic-needs/how-much-care-will-you-need
—
This blog contains a hypothetical example used for illustrative purposes only. It is not representative of any specific investment or combination of investments. There is no assurance or certainty that any investment or strategy will be successful in meeting objectives.